
Best Places to Retire in the US: A Decision Framework
by 10 Federal Storage
Published on September 3, 2026
Search for the best places to retire and you will get roughly the same twelve cities from roughly the same twelve articles. Charleston, Tampa, Scottsdale, a college town, and one surprisingly cheap Rust Belt city for balance. Each entry gives you a population figure, a median home price, a cost-of-living percentage, and four hundred words about golf courses and botanical gardens. Then you close the tab and you still have no idea what to do.
The problem is not that those lists are dishonest. The problem is that they are answering a question nobody actually has. Almost nobody is trying to decide between Ann Arbor and Youngstown in the abstract. What people are actually trying to work out is narrower and harder: whether the specific move they are already considering will still look like a good decision in eight years, after the tax situation shakes out, after the insurance renewal arrives, after one spouse has a health event, and after the reality of being nine hundred miles from a daughter sets in.
This post is built for that question instead. The first two thirds is a framework: the nine factors that actually determine whether a retirement relocation works, with the four that get skipped in every ranking we could find covered in real detail. Those four are how Medicare and Medicare supplement coverage behave when you cross a state line, what federal law does and does not require of an age-restricted community, why property tax relief you have spent twenty years earning may not follow you, and how to read natural hazard exposure before an insurer reads it for you.
The last third applies the framework to specific markets, including a section on four widely recommended retirement destinations we would think hard about, and a section on the downsizing math that decides what actually fits in the house you are moving into. We are a storage company, so we will be straight with you about that part: there is a section near the end that tells you when renting a unit during a retirement move is a mistake, and it is longer than the section telling you when it helps.
Table of Contents
- Why Most Best Places to Retire Lists Will Not Help You Decide
- The Nine Factors That Actually Decide Whether a Retirement Move Works
- How States Tax Retirement Income: Social Security, Pensions, and Withdrawals
- The Estate and Inheritance Tax Layer That Almost No Retirement List Mentions
- Property Taxes: Why the Headline Rate Is the Least Useful Number
- The Florida Save Our Homes Cap and Why Portability Stops at the State Line
- Texas Property Tax Relief for Homeowners 65 and Older
- Medicare Does Not Move With You the Way You Think It Does
- Medigap Underwriting: The Most Expensive Mistake in a Retirement Move
- How to Evaluate Healthcare Access Beyond a Hospital Name
- Homeowners Insurance and Natural Hazard Exposure
- What Federal Law Actually Says About 55 and Over Communities
- HOA Dues, CDD Fees, and Club Charges: The Costs That Are Not the Mortgage
- Climate, Season Length, and What Weather Does to a Daily Routine
- Walkability, Transit, and Planning for the Year You Stop Driving
- Distance From Family and the Reverse Migration Problem
- Coastal and Sunbelt Markets Worth Putting on Your List
- Mountain and Inland West Markets Worth Putting on Your List
- College Towns and Medical Hub Markets Worth Putting on Your List
- Affordable Markets Worth Putting on Your List
- Popular Retirement Cities We Would Think Twice About and Why
- Snowbirding, Split Residency, and Establishing Legal Domicile
- How to Test Drive a City Before You Commit to It
- The Downsizing Arithmetic: What Actually Fits in a Retirement Home
- When Storage Makes Sense in a Retirement Move and When It Does Not
- Frequently Asked Questions About Retiring in the US
- Planning Your Retirement Move
Why Most Best Places to Retire Lists Will Not Help You Decide
Start with a concrete example, because the failure mode is easier to see than to describe. The Extra Space Storage guide to the best cities for retirement carries a current update stamp and lists twelve cities, each with a median home purchase price. Its Youngstown, Ohio entry lists that price at $46,900. Current market data for Youngstown does not support that figure: home value indices for the city sit above $70,000 and recent median sale prices have run past $125,000. The number in that article is not slightly stale. It is a snapshot from around the time the article was first published, several years ago, carried forward unchanged under a fresh date.
We are not pointing that out to score a point. We are pointing it out because it is the structural problem with the entire genre. When a retirement guide is built as a stat block, the stat block is the whole product, and stat blocks rot. A cost-of-living percentage, a median rent, and a crime percentile are all true for about a year. Publishing them and then updating the date is the cheapest possible way to look current, and it is the reason so many of these pages read as authoritative and turn out to be useless the moment you check anything.
There is a second problem, quieter than the first. Nearly every one of these lists is ordered alphabetically or by nothing in particular, while claiming a methodology. The Extra Space list runs Ann Arbor, Charleston, Clearwater, Colorado Springs, Daytona Beach, Fort Wayne, Harrisburg, Lancaster, Pittsburgh, Scottsdale, Tampa, Youngstown. That is the alphabet. There is no ranking because there is no ranking to make: the cities were not compared against each other on any dimension, they were assembled and then described.
The third problem is the one that costs real money. Not one of the ranking pages we reviewed for this post mentions what happens to your Medicare supplement coverage when you move to a new state. Not one explains that the property tax protection you have accumulated over two decades does not cross a state line. Not one accurately describes the federal rules that govern who can live in an age-restricted community, which matters enormously to couples with an age gap between them. Not one discusses natural hazard exposure or the insurance market that prices it, which is now the fastest-growing line item in a lot of retirement budgets.
Those four omissions are not small print. They are the difference between a move that works and a move you spend the next five years quietly regretting. So this post spends most of its length on them, and treats the city recommendations as what they actually are: a starting shortlist that you then run through the framework yourself, with current numbers you pull the week you are deciding rather than numbers we printed at some point in the past.
One more framing note. We are going to use qualitative descriptions of markets rather than pinned dollar figures wherever we reasonably can, and where a number genuinely matters we will tell you which agency publishes the current one instead of copying today’s into a page that will still be online in four years. That is a deliberate choice and it makes this post less immediately satisfying to skim. It also makes it correct for longer.
The Nine Factors That Actually Decide Whether a Retirement Move Works
Here is the framework the rest of this post is organized around. The order matters: the factors near the top are the ones that are hard or impossible to fix after you have moved, and the ones near the bottom are the ones you can adjust to.
- Health coverage continuity. Whether your current Medicare arrangement survives the move intact, and what your options actually are if it does not. This is first because it is the only item on the list where a wrong move can be permanently unwinnable. Covered in Sections 8 and 9.
- Healthcare access in the specific place, not the state. Specialist depth, hospital quality, emergency response times, and whether the systems near you participate in the plan you can actually get. Section 10.
- Total tax picture, not the headline. Income tax treatment of the specific income you draw, property tax mechanics including relief programs and caps, sales tax on the things you buy weekly, and estate or inheritance tax where it applies. Sections 3 through 7.
- Hazard exposure and what it costs to insure. Wind, flood, wildfire, and the availability of coverage at any price. Section 11.
- Housing type and its legal structure. Age-restricted, deed-restricted, or neither, and what the governing documents actually require of you and of anyone who might come live with you. Sections 12 and 13.
- Recurring non-mortgage housing cost. HOA dues, community development district assessments, club membership requirements, and special assessments. Section 13.
- Climate as a daily routine rather than a vacation. Not the average temperature, but how many days a year the weather stops you from doing the thing you moved there to do. Section 14.
- Mobility after driving. Whether the place still functions for you in the year you stop driving, which for most people arrives earlier than expected. Section 15.
- Distance from the people who will show up. Not distance from family in the abstract, distance from whoever would drive over at ten at night. Section 16.
Notice what is not on the list. Restaurants, museums, golf courses, farmers markets, and festivals do not appear anywhere, and they take up most of the word count in every competing guide. That is not because amenities do not matter. It is because amenities are the easiest thing to research, the easiest thing to verify on a visit, and the least likely thing to be the reason a move failed. Nobody moves back after two years because the theater season was disappointing. People move back because a hospital did not have the specialist they needed, because the insurance renewal doubled, or because they got sick and their kids were four states away.
Use the framework as a scoring exercise if it helps. Take three candidate cities, rate each on the nine factors, and pay attention to any factor where a candidate scores badly on one of the top four. Those are effectively disqualifying, because they are the ones you cannot fix from inside the house you just bought.
How States Tax Retirement Income: Social Security, Pensions, and Withdrawals
Retirement guides love to say a state is tax-friendly. It is nearly a meaningless phrase, because retirement income is not one thing. A household drawing entirely from Social Security has a completely different state tax profile than a household drawing a public pension, which is different again from one taking large traditional IRA distributions. States treat those three categories separately and inconsistently.
Break your own income into the categories that states actually distinguish:
- Social Security benefits. The large majority of states do not tax these at all. As of the most recent tax year, the short list of states that still tax some Social Security income is generally reported as Colorado, Connecticut, Minnesota, Montana, New Mexico, Rhode Island, Utah, and Vermont, with West Virginia having completed a phase-out. Even within that group, most use income thresholds or age rules that exempt the majority of retirees outright. Worth noting honestly: sources disagree on the exact count, because several states have been phasing out these taxes on different schedules and the published lists lag the legislation. Confirm with the revenue department of any state you are seriously considering.
- Private pensions and annuity income. Treated very differently state to state. Some exempt it entirely, some offer an age-triggered deduction, some tax it as ordinary income. Pennsylvania is unusually generous here and it is the reason that state shows up on retirement lists so often.
- Public and military pensions. Frequently carved out for better treatment than private pensions, sometimes dramatically. If you have one, do not assume the private pension rules apply to you.
- Traditional IRA and 401(k) withdrawals. Generally the least protected category. A state that exempts Social Security completely may tax every dollar you pull from a traditional account. If your plan involves large withdrawals in your sixties, or Roth conversions, this is the category that dominates your state tax bill and it is the one the tax-friendly labels almost never address.
- Capital gains and investment income. Relevant if selling a long-held home or a taxable portfolio is part of the plan. A handful of states with no wage income tax still reach investment income in some form.
The practical exercise is straightforward and almost nobody does it. Take last year’s actual return, and for each state on your shortlist, work out what the same income would have produced. Not the rate, the bill. States with no income tax at all are the obvious floor, but a state with a moderate rate and generous retirement carve-outs can beat a no-income-tax state that funds itself through property and sales tax, particularly if you plan to own a home of any size.
The other thing to check, and it costs nothing: the direction of travel. Several states have moved aggressively in the last few years to exempt Social Security and broaden retirement deductions, explicitly to attract and retain older residents. A state that has just made a change is unlikely to reverse it soon. A state where the exemption is under active legislative debate is a different proposition. Your state revenue department publishes the current rules and a tax professional who works in the destination state is worth the consultation fee before you commit to a move of this size. Nothing in this section is tax advice and none of these figures should be relied on for planning without that confirmation.
The Estate and Inheritance Tax Layer That Almost No Retirement List Mentions
This is the clearest example of what gets lost when a retirement guide is written as a tourism piece. Several of the cities that appear on every best-places-to-retire list sit in states with a state-level estate tax or inheritance tax. Almost none of those guides mention it, including the ones that spend a paragraph praising the same state’s treatment of pension income.
The two taxes are different and the difference matters:
- An estate tax is levied on the estate itself before distribution, above an exemption threshold set by the state. The state threshold is often far below the federal one, which is why a household that would owe nothing federally can still owe at the state level.
- An inheritance tax is levied on the person receiving the money, and the rate typically depends on their relationship to you. A surviving spouse is normally exempt. Children and other direct descendants usually pay a low rate. Siblings pay more. Nieces, nephews, friends, and unrelated beneficiaries pay the most.
Pennsylvania is the case worth understanding, because three Pennsylvania cities appear on the Extra Space list and the state’s inheritance tax appears nowhere in that article despite a full paragraph on how Pennsylvania does not tax retirement income. Both things are true simultaneously. The income tax treatment is genuinely excellent for retirees. There is also a state inheritance tax with tiered rates by relationship. If you are moving to Pennsylvania and plan to leave assets to anyone other than a spouse, that is a real planning consideration and it belongs in the same conversation as the income tax benefit, not omitted from it.
A few states have repealed these taxes recently and others have adjusted thresholds, so the map moves. What does not change is the analysis you should run: identify whether your destination state has an estate tax, an inheritance tax, both, or neither; find the current exemption threshold; and check the rate that would apply to your actual intended beneficiaries rather than to a spouse. If the answer is uncomfortable, that is a conversation for an estate attorney licensed in that state, not a reason to abandon the move outright. Trusts, gifting strategy, and titling all interact with these rules in ways that are entirely outside the scope of a blog post.
The point of raising it here is narrower: it should be on your list of questions, and if you only read retirement city guides you will never learn that it exists.
Property Taxes: Why the Headline Rate Is the Least Useful Number
Every retirement guide quotes a state’s average effective property tax rate. It is the wrong number in three separate ways, and understanding why is the difference between an estimate that is roughly right and one that is off by half.
First, property tax is local, not state. The state average blends a county with almost no municipal services against a county funding three school districts and a hospital authority. Two towns forty minutes apart in the same state routinely differ by more than the gap between two states. The number you need is the effective rate for the specific taxing jurisdiction of the specific address, and every county assessor in the country publishes it.
Second, the rate is applied to an assessed value that may bear little relationship to market value. States use assessment ratios, assessment caps, and revaluation cycles that vary enormously. A state with a scary-sounding rate applied to forty percent of market value can produce a smaller bill than a low-rate state that assesses at full market value every year. South Carolina is the standard illustration here, applying a substantially lower assessment ratio to owner-occupied primary residences than to other property, which is a large part of why the state reads as retiree-friendly on property tax despite unremarkable headline rates.
Third, and most consequentially, the rate ignores relief programs. Most states offer some combination of the following to older homeowners, and they are frequently worth more than the difference between two states’ rates:
- Homestead exemptions. A fixed dollar amount or percentage of value removed from taxation on a primary residence. Many states offer an additional layer specifically for homeowners past a certain age.
- Assessment caps. A limit on how fast the assessed value can rise in a year regardless of what the market does. Over a long retirement this compounds into the single largest tax benefit most retirees ever receive.
- Tax ceilings or freezes. A hard lock on the dollar amount of some portion of your bill, usually triggered by age. Distinct from an assessment cap, and usually more valuable.
- Circuit breakers. Relief that phases in based on income rather than age, refunding or crediting property tax above a set share of household income.
- Deferral programs. Options that let an older homeowner postpone payment entirely, with the deferred amount plus interest becoming due when the property is sold or transferred. These are genuinely useful in a cash-flow crunch and genuinely consequential for what your heirs receive, which is why they should be discussed with an advisor rather than adopted casually.
Two rules that catch people out. Relief is almost never automatic: nearly all of these require an application, usually to the county appraisal or assessment district, usually with a filing deadline. Turning the qualifying age does not switch anything on by itself. And relief is almost never portable across state lines, which is the subject of the next two sections.
Confirm current exemption amounts, eligibility ages, and filing deadlines with the county assessor or the state revenue department for any address you are considering. Several states changed these amounts materially within the last two legislative cycles, and any figure printed in a blog post, including ours, should be treated as a prompt to go check rather than as a number to plan around.
The Florida Save Our Homes Cap and Why Portability Stops at the State Line
Florida is the most-searched retirement destination in the country and its property tax system is widely misunderstood, including by people who already live there. It is worth walking through properly, because the same structural logic applies in several other states and because the most important fact about it is one almost nobody mentions.
Florida’s Save Our Homes provision, which lives in Article VII, Section 4 of the state constitution and is implemented in Section 193.155 of the Florida Statutes, caps the annual increase in the assessed value of a homesteaded property at three percent or the change in the Consumer Price Index, whichever is lower. Market value can do whatever the market does. The taxable assessed value cannot climb faster than the cap.
Over a long ownership in an appreciating market, the gap between market value and assessed value becomes enormous. That gap is the benefit. A household that has held a homesteaded Florida property since the mid-2000s may be sitting on hundreds of thousands of dollars of sheltered value, and the annual tax saving that represents is often the single largest line item in their favor.
Then comes portability, which is the part that gets explained badly. Florida allows a homesteaded owner to carry accumulated Save Our Homes benefit to a new Florida homestead, currently subject to a statutory maximum and a filing window measured in tax years from the abandonment of the previous homestead. The transfer is claimed on a specific form filed with the new county’s property appraiser, and missing the window forfeits the accumulated benefit permanently on the new purchase.
Three things about portability that matter directly to a retirement move:
- It does not apply if you are moving to Florida from another state. Portability transfers a Florida benefit to a new Florida homestead. If you have never held Florida homestead, there is nothing to transfer. You start at full market value on your new home and begin accumulating the cap benefit from that year forward. Every article that describes Save Our Homes as a reason to retire to Florida is, on this specific point, describing a benefit that will take you fifteen years to earn.
- Downsizing transfers only a proportional share. The formula for moving to a less expensive home carries a fraction of your accumulated benefit rather than the whole thing. This surprises retirees constantly, because downsizing is exactly what most of them are doing.
- The clock starts when you abandon the old homestead, not when you close on the new one. If you are selling now and buying later, that timing gap is coming out of your window.
The broader lesson generalizes past Florida. Accumulated property tax protection is a state-level asset. It is often the largest single financial benefit a long-tenured homeowner holds, and in almost every case, crossing a state line destroys it. If you have lived somewhere a long time under a cap or a freeze, quantify what you are giving up before you compare mortgage payments. Your county assessor can tell you the difference between your current market and assessed values, and that difference multiplied by your local rate is the annual number you are walking away from.
Florida’s Department of Revenue and each county property appraiser publish current cap percentages, transfer maximums, deadlines, and forms. Confirm all of it directly with them. This section describes mechanisms, not amounts, and it is not tax advice.
Texas Property Tax Relief for Homeowners 65 and Older
Texas is the other state where the property tax conversation is genuinely decisive, and it runs the opposite way from Florida’s. Texas levies no state income tax, which is the headline, and funds local government substantially through property tax, which is the catch. For a retiree on a fixed income, the property tax bill is the one that hurts, and it is also the one Texas offers the most machinery to reduce.
Three mechanisms stack, and they are distinct from one another:
- The general residence homestead exemption removes a set amount of value from school district taxation on a primary residence. The amount has been raised more than once by recent legislation and by statewide ballot proposition, so confirm the current figure with the Texas Comptroller rather than any secondary source.
- An additional exemption for homeowners 65 and older stacks on top of the general one, again for school district taxes. Homeowners who qualify as disabled generally receive the same additional exemption regardless of age.
- The school tax ceiling is the one that matters most over a long retirement and the one people understand least. Once you qualify for the over-65 exemption, the dollar amount of your school district tax is frozen at that year’s level. It does not rise when your appraised value rises and it does not rise when the school tax rate rises. Over twenty years, the ceiling routinely protects more money than the exemption itself.
Four practical details that decide whether any of this reaches you:
- None of it is automatic. Turning 65 does not trigger the exemption or the ceiling. You file an application with your county appraisal district, using the Comptroller’s residence homestead application form, and you provide identification with an address matching the property. If you already have a general homestead exemption on file, confirm separately that the over-65 status and the ceiling were actually recorded. People assume they switched on and find out years later that they did not.
- The ceiling covers school taxes only. City, county, hospital district, and other special district bills can still rise. Protesting your appraised value annually still has value even after the ceiling is in place, because it affects everything the ceiling does not.
- The ceiling is transferable within Texas. Move to another Texas primary residence and you can carry the same percentage of benefit, using a tax ceiling certificate obtained from your former appraisal district. Like Florida’s portability, it stops at the state line.
- A deferral option exists. Texas allows qualifying homeowners 65 and older to defer property tax on a homestead, with interest accruing and the balance due on sale or transfer. It is a real tool for a genuine cash-flow problem and a real reduction in what your heirs inherit. Discuss it with an advisor before using it.
- Surviving spouse provisions exist and have their own age conditions. If this is relevant to your household, ask the appraisal district specifically rather than assuming.
Texas markets that show up regularly on retirement shortlists include the Hill Country and the corridor north of Austin, where large master-planned active adult communities have concentrated. If a specific Texas suburb is on your list, our neighborhood guide to Georgetown, Texas covers one of the best-known of those markets in detail, including how the active adult communities there are structured.
All exemption amounts, ceiling rules, forms, and deadlines should be confirmed with the Texas Comptroller and your county appraisal district. Amounts changed recently and will likely change again.
Medicare Does Not Move With You the Way You Think It Does
Medicare is a federal program, so people reasonably assume it works identically everywhere and that a move is administratively trivial. Original Medicare, meaning Part A and Part B, mostly does behave that way. Everything layered on top of it does not, and the layers are where nearly all of your actual coverage lives.
Original Medicare travels well. Part A and Part B are accepted by any provider in the country who accepts Medicare assignment. Move anywhere and your Part A and Part B coverage continues. You update your address with Social Security and that piece is done.
Medicare Advantage does not travel. Medicare Advantage plans are sold and priced by service area, and service areas are typically defined at the county level. The plan you have in one county may not be sold in the county you are moving to, and even where the same insurer operates, the plan design, the premium, the provider network, the drug formulary, and the supplemental benefits are all different products. Moving out of your plan’s service area triggers a Special Enrollment Period, which gives you a defined window to choose new coverage. That window is a protection, and it is also a deadline. Missing it creates gaps.
Part D prescription drug plans are also regional. Premiums, formularies, and preferred pharmacy networks all vary by region. A drug that is on a preferred tier in your current plan can be on a specialty tier in the plan available where you are moving. If anyone in the household takes an expensive maintenance medication, this is worth pricing specifically before you sign anything, using the plan finder tools on the official Medicare site with your actual drug list and your destination ZIP code.
Medigap policies mostly travel, with a large asterisk. A standardized Medicare supplement policy generally continues to work anywhere in the country that accepts Original Medicare, so if you already hold one you can usually keep it. But your premium may change, because Medigap pricing varies by state and by rating method. And if you want or need to switch to a different policy after you move, you run directly into the underwriting problem that the next section is about. There is one specific exception worth knowing: Medicare SELECT policies use a local network, so moving out of that network’s area does create a right to change plans.
The sequencing advice that follows from all of this is unglamorous and it saves people a lot of money. Work out your health coverage before you choose the house, not after. For every city on your shortlist, check which Medicare Advantage plans are actually sold in that county, whether the health systems you would realistically use participate, and what a Part D plan covering your actual medications costs there. Do this at the county level. Two suburbs of the same metro can sit in different counties with materially different plan availability, and that is not a distinction any retirement city guide will ever make for you.
Every state operates a State Health Insurance Assistance Program, usually called SHIP, offering free unbiased counseling on exactly these questions. They are the right people to call, they do not sell anything, and using them costs nothing. This section describes how the program is structured; it is not insurance advice and it cannot tell you what your own situation requires.
Medigap Underwriting: The Most Expensive Mistake in a Retirement Move
This is the single most consequential fact in this post and we could not find it mentioned in any competing best-places-to-retire guide. If you read nothing else here, read this.
Every person eligible for Medicare gets a one-time Medigap Open Enrollment Period. It runs for six months, beginning the first month you are both 65 or older and enrolled in Part B. During that window, an insurer must sell you any Medigap policy it offers in your state. It cannot refuse you, it cannot charge you more because of your health history, and it must cover pre-existing conditions on the terms of the policy.
After those six months close, that protection is gone. In most states, insurers may medically underwrite a Medigap application. They can ask about your health history, they can decline you outright, and they can charge more based on what they find. The window does not reopen annually. It is not tied to the fall Medicare open enrollment period that gets advertised every year, which governs Medicare Advantage and Part D and has nothing to do with Medigap underwriting.
Here is where the retirement move comes in. Moving to a new state does not create a new guaranteed issue right. A cross-country relocation is not, by itself, a qualifying event for Medigap. Federal guaranteed issue rights exist, but they are a short and specific list built around losing coverage you already had, an insurer leaving the market or going insolvent, a plan breaking Medicare’s rules, and a limited trial right for people who tried Medicare Advantage when first eligible and want to switch back within their first year. Relocating is not on that list, except in the Medicare SELECT case mentioned above.
The scenario this produces is common enough to be worth spelling out. A couple retires and moves. They have been on a Medicare Advantage plan for several years. The plan is not offered in their new county, or it is offered but the local hospital system does not participate. They decide to switch to Original Medicare plus a Medigap policy, which will let them use any provider who accepts Medicare. They apply. One of them has a condition that has developed in the intervening years. The application is declined, or comes back priced far above what they budgeted. They are now on Original Medicare with no supplement, exposed to the twenty percent coinsurance with no annual out-of-pocket maximum, or they are back in a Medicare Advantage plan whose network does not include the doctor they wanted.
That outcome is not reversible by moving back. It is a health status problem, not a geography problem, and it is why this factor sits at the top of the framework in Section 2.
Some state-level protections exist and they vary a great deal. A handful of states require year-round or annual guaranteed issue regardless of health. Another group has enacted so-called birthday rules giving beneficiaries a short annual window around their birthday to switch policies without underwriting, usually with conditions attached about moving only to a plan of equal or lesser benefits. These protections change, they attach to the state you live in rather than the state you came from, and no summary written at one point in time should be trusted for a decision this size.
What to actually do:
- Find out what your six-month window status is. If you are approaching 65 and considering a move, know that this window is one-time and that where you are living when it opens determines which state’s rules and which state’s carriers you are working with.
- Before you commit to a destination, call the SHIP office in that state. Ask directly what Medigap protections exist there beyond the federal minimum, and whether any of them would apply to your situation. This is free.
- Ask the same question about the state you are leaving, because if you have unusually strong protections where you are now, giving them up is a real cost of the move that belongs in the comparison.
- If a switch from Medicare Advantage to Original Medicare plus Medigap is any part of your plan, sequence it deliberately and get advice on the order of operations before you list your house, not after you have closed on a new one.
We are a storage company and we are explicitly not qualified to advise anyone on insurance. What we can tell you is that this rule exists, that it is federal, and that no city ranking is going to mention it to you. Take it to a SHIP counselor or a licensed independent broker who does not represent a single carrier.
How to Evaluate Healthcare Access Beyond a Hospital Name
Retirement guides handle healthcare by naming a hospital and linking to a best-hospitals ranking. That tells you almost nothing about whether you will be able to get care. Here is what to actually check, in rough order of how often it turns out to be the binding constraint.
Whether the practices are accepting new Medicare patients. This is the real bottleneck in a large number of desirable retirement markets, and it is invisible from the outside. A metro can have excellent hospitals and a primary care market where the wait for a new patient appointment runs many months because retiree in-migration has outpaced physician supply. The test is direct: call three primary care practices in the area you are considering, say you are relocating and on Medicare, and ask when their next new patient appointment is. The answers will tell you more than any ranking.
Specialist depth in the specialties you specifically need. A general hospital ranking averages across service lines. If someone in the household has a cardiac condition, or a rheumatologic condition, or is in cancer surveillance, the question is not whether the hospital is good, it is how many practicing specialists in that discipline are within a reasonable drive and whether any of them are accepting patients. Rural and semi-rural retirement markets, which is a lot of the affordable ones, are frequently thin in exactly these areas.
Distance and travel time to a hospital with an emergency department, measured honestly. Not the map distance, the actual drive at the time of day you would be making it. In coastal and mountain markets, seasonal traffic can double it.
Whether the systems you would use participate in the coverage you can actually get. This is the intersection with Section 8 and it is where plans fall apart. It does not help to be twenty minutes from an excellent hospital that is out of network on every Medicare Advantage plan sold in your county.
Continuity of care during the transition. Ask your current specialists whether they can recommend anyone in the destination market, ask what records need to transfer and in what form, and expect the process to take longer than you think. Schedule your establishing appointments before you move if you possibly can. New patient waits do not shorten because you have already signed a mortgage.
The care continuum, not just acute care. Home health availability, outpatient rehabilitation, and skilled nursing capacity all matter enormously in the second half of a retirement and none of them appear in a hospital ranking. If you are choosing a place to be for twenty-five years, look at what exists for the years when the question is not which hospital but who comes to the house.
A reasonable shortcut: pick the two health concerns most likely to define your next decade, and evaluate each candidate city on those two specifically rather than on healthcare as a general category. That produces a genuinely different shortlist than the one you get from reading hospital rankings, and it is closer to the decision you are actually making.
Homeowners Insurance and Natural Hazard Exposure
For a lot of retirees who moved to the Sunbelt over the last decade, the largest unbudgeted increase in their cost of living has not been groceries or healthcare. It has been the homeowners insurance renewal. This deserves a section because it is now big enough to change the answer on where to retire, and because the retirement guides have not caught up to it.
The Government Accountability Office examined homeowners insurance premiums nationally and found that while premiums broadly tracked inflation, they rose considerably more in disaster-prone areas. That is the pattern in a sentence: the national average understates what happened in exactly the markets retirees have been moving to.
Here the sources genuinely disagree, and rather than pick one we will show you the disagreement, because it tells you something about how to read any figure in this space. Consumer insurance data aggregators have put Florida’s average annual homeowners premium in the mid-four figures to over eight thousand dollars depending on methodology, coverage assumptions, and whether wind coverage is included. Analyses built on filings with the state insurance regulator have produced substantially lower statewide averages over the same period. Both are defensible. They are measuring different things: different dwelling coverage amounts, different deductibles, different treatment of the state-backed insurer, different treatment of properties that cannot get coverage in the standard market at all.
The lesson is not that one source is lying. It is that a state average is close to useless for your decision, because your premium will be set by your specific address, your specific construction, your specific roof age, and your specific distance to water. Get a real quote on a real address before you make an offer.
Things to check that most buyers do not:
- Flood is a separate policy. Standard homeowners policies exclude flood damage, including storm surge. Coverage comes through the National Flood Insurance Program or a private flood insurer. NFIP pricing has moved to a methodology that prices individual property risk rather than assigning a rate by flood zone alone, which means two houses on the same street can price very differently.
- Wind and hurricane deductibles are usually percentages, not dollar amounts. A percentage deductible on a coastal policy can represent a very large out-of-pocket exposure on a single claim. Read that line specifically.
- Availability is a separate question from price. In some markets the binding constraint is not what coverage costs but whether a carrier will write it at all, which pushes owners into state-backed insurers of last resort with their own coverage limitations.
- Roof age and construction year drive underwriting hard in wind-exposed markets. An otherwise lovely older home can be effectively uninsurable or insurable only at a punishing rate. Ask about this before you fall in love with the house.
- Wildfire exposure has produced the same dynamic in parts of the interior West that hurricane exposure produced on the coasts, with similar effects on availability.
For an independent read on hazard exposure that is not produced by anyone selling you anything, FEMA publishes the National Risk Index, a free public tool that rates every county and census tract in the country for expected annual loss across eighteen natural hazards, alongside measures of social vulnerability and community resilience. It is the closest thing to a neutral baseline available, it costs nothing, and it takes ten minutes. Run every city on your shortlist through it before you run any of them through a real estate site.
One honest caveat on all of this: insurance markets move fast in both directions. Some states have seen rate filings turn downward after regulatory changes, and a market that looked impossible three years ago may look different now. That is another argument for getting a current quote on a current address rather than trusting any published average, including the ones in this section.
What Federal Law Actually Says About 55 and Over Communities
Age-restricted communities are a large share of what people are actually buying when they retire, and the rules governing them are almost universally misdescribed. The confusion causes real problems, particularly for couples with an age gap and for anyone who might one day need an adult child or a caregiver to live with them.
The framework comes from the Fair Housing Act as amended by the Housing for Older Persons Act of 1995, implemented in federal regulation at 24 CFR Part 100, Subpart E. The Fair Housing Act generally prohibits housing discrimination on the basis of familial status, meaning against households with children. Age-restricted housing is an exemption from that prohibition, and it is available in three forms.
The 62 and older exemption. Housing intended for and occupied solely by persons 62 or older. This one is strict in a way that catches couples out. Under HUD’s regulations, a community operating under this exemption would have to refuse an applicant who is 62 if their spouse is 59. If there is an age gap in your household and you are looking at a 62-plus community, ask this question explicitly and in writing before you go any further.
The 55 and older exemption. This is the common one, and it has three prongs that must all be satisfied at once. At least 80 percent of occupied units must be occupied by at least one person aged 55 or older. The community must publish and adhere to policies and procedures demonstrating an intent to operate as housing for people 55 and older. And it must comply with HUD’s rules for verifying occupancy, which in practice means surveying residents on a regular cycle and keeping the records.
Publicly funded senior housing under a program HUD has determined is specifically designed for older persons, which operates under its own rules.
Four consequences of the 80 percent rule that matter to buyers and that sales offices do not always explain clearly:
- Twenty percent of occupied units do not need anyone 55 or older. The exemption does not require a fully age-restricted population. It requires 80 percent. That headroom is real and communities manage it deliberately.
- Federal law does not set the minimum age for other occupants. Within a qualifying unit, the law does not restrict the ages of the other people living there. What keeps children out of most active adult communities is not HOPA, it is the community’s own governing documents, which typically impose a minimum age for permanent residents and rules for guest stays. Those documents vary enormously and they are what you actually have to read.
- The exemption is conditional and can be lost. A community that falls below the 80 percent threshold and fails to recover it loses the exemption and becomes subject to the full familial status protections of the Fair Housing Act. Ask the association whether they conduct the required occupancy survey on schedule and whether they are comfortably above the threshold, not just barely.
- Some states impose stricter requirements than federal law. California, for instance, applies a more restrictive standard than the federal 80 percent rule. Check the state as well as the federal framework.
The practical questions to ask a sales office, and to then verify in the recorded governing documents rather than taking verbally:
- Which exemption does this community operate under, 55 and older or 62 and older?
- What is the minimum permanent resident age set by the governing documents, as distinct from the federal rule?
- What are the rules on long-term guests, and what counts as long-term?
- If an adult child or a live-in caregiver needed to move in, under what conditions is that permitted?
- What happens to occupancy rights if the older spouse dies first?
- When was the last occupancy survey and what did it show?
That last set of questions is the one that separates a community you will be happy in from one you will find out about later. Nothing here is legal advice, and if any answer is ambiguous, a real estate attorney reading the recorded declarations before closing is money well spent.
HOA Dues, CDD Fees, and Club Charges: The Costs That Are Not the Mortgage
In the master-planned communities that dominate retirement housing, the mortgage is frequently the smallest of several recurring housing costs and the only one that is fixed. The others move, and they move in one direction.
Sort them out before you buy, because they are not interchangeable and they are not all disclosed with the same prominence:
- HOA or association dues. The regular assessment funding common area maintenance, amenities, and administration. Ask what is included, because the range is enormous. In some communities dues cover exterior maintenance, roof reserves, and landscaping. In others they cover a gate and a pool.
- Community development district or special district assessments. Common in Florida and used elsewhere under other names, these fund the infrastructure the developer built, roads, drainage, utilities, and they typically appear on the property tax bill rather than the HOA bill. They can persist for decades and they can be substantial. Two identical houses in the same community can carry different assessments depending on when their section was developed and how it was financed. Ask specifically whether the property carries a district assessment, what the annual amount is, and when the bond is scheduled to be retired.
- Mandatory club or golf memberships. Some communities require a membership as a condition of ownership regardless of whether you use it. Some require a one-time initiation contribution at closing. Some have a transfer fee on resale. All of this is in the documents.
- Capital contributions and transfer fees. One-time charges triggered by purchase or sale, sometimes several months of dues, sometimes a percentage of the price.
- Special assessments. The one that actually causes financial distress. When a reserve fund is inadequate and a major repair comes due, the association levies a one-time charge on every owner. In older communities this can be a five-figure demand with limited notice.
The single most useful thing you can do before buying into any association is read the reserve study and the last two years of association meeting minutes. The reserve study tells you what major components exist, when they are due for replacement, and whether the association has been funding for it. The minutes tell you what the board is actually arguing about, which is where a coming special assessment shows up first. Both are normally available to a prospective buyer on request, and an association that is reluctant to provide them has told you something.
Also ask about the history of dues increases over the last five years rather than only the current amount. A community whose dues have risen steadily is not necessarily badly run, it may simply be funding reserves honestly, which is better than the alternative. A community with flat dues and a thin reserve fund is where the special assessment is coming from.
Climate, Season Length, and What Weather Does to a Daily Routine
Retirement guides describe climate the way a travel brochure does: mild winters, year-round sunshine, four distinct seasons. None of that tells you what you need to know, which is how many days a year the weather prevents you from doing the specific thing you moved there to do.
Reframe it as a usable days count. If you are moving somewhere to walk every morning, play golf, garden, fish, or ride a bike, the relevant number is how many mornings a year those activities are actually pleasant. That number is often lower than the marketing suggests, and it is low for different reasons in different places.
- Deep South and Gulf Coast markets trade a winter problem for a summer one. Outdoor life from late autumn through early spring is genuinely excellent. Mid-June through mid-September, a meaningful share of the population becomes largely indoor between mid-morning and evening. If your mental picture of retirement is outdoors, count the months honestly rather than counting the winters you are escaping.
- Desert Southwest markets run the same trade with a longer and hotter summer, offset by extremely low humidity and a winter that is close to ideal. The heat is genuinely different from Gulf Coast heat and some people tolerate it far better. Visit in July before deciding, not in February.
- Southern Appalachian and Piedmont markets tend to have the most balanced usable-days profile in the eastern half of the country: real but short winters, long shoulder seasons, and summers that are hot but not incapacitating. This is a large part of why the Carolinas, north Georgia, and east Tennessee keep gaining retirees.
- Interior West and mountain markets offer low humidity, high sunshine, and cold, dry winters. Snow removal, ice on driveways, and elevation are the practical considerations. Elevation in particular is worth discussing with a physician if anyone in the household has a cardiac or pulmonary condition.
- Northern and Midwestern markets have the winter everyone expects and, in exchange, summers that are frequently the best in the country and a cost basis that is dramatically lower. If your social life is indoors anyway, the winter penalty is smaller than it looks on paper.
Two practical considerations that get missed. First, seasonal population swings change the character of a place more than weather does. A market that doubles in population between January and March has a different grocery store, a different restaurant wait, a different emergency room, and a different commute in season than out of it. Visit in both. Second, air quality is now a real variable in parts of the interior West during wildfire season, and it is the kind of thing that does not show up in a climate average but does show up in a summer where you cannot go outside.
Walkability, Transit, and Planning for the Year You Stop Driving
Most people choose a retirement home for the version of themselves who is currently driving. The house is chosen for the sixty-eight-year-old and lived in by the eighty-two-year-old, and the two have very different requirements.
This is not a hypothetical. Nearly everyone eventually stops driving, whether by choice, by a physician’s recommendation, or after an incident. The date is unknowable in advance, and the decision you make now about where the house sits either creates a crisis on that date or does not. It is worth thinking about explicitly because it is entirely solvable now and largely unsolvable later.
The question to ask of any candidate address is direct: if neither of us could drive, what happens? Work through it concretely.
- Groceries and pharmacy. Deliverable, within walking distance, or dependent on someone driving you? Delivery coverage varies more than people expect outside metro cores.
- Medical appointments. Is there paratransit or a senior transportation program in the county, what does it cost, how far ahead must it be booked, and does it go where your doctors are? Many counties run one and almost nobody researches it before moving.
- Social contact. This is the one that determines quality of life and the one nobody plans for. If getting to a coffee shop, a church, a library, or a friend’s house requires a car, then losing the car means losing all of it at once. A neighborhood where a few of those are reachable on foot is a different retirement.
- Household maintenance. A large lot in a car-dependent exurb is fine at sixty-eight. Consider what it requires at eighty-two and what it costs to have done.
The related structural question is the house itself. Single-level living, a zero-step entry somewhere on the property, a doorway width that accommodates a walker, a bathroom that can take grab bars without a renovation, and a laundry that is not in a basement are all cheap to specify when buying and expensive to retrofit. None of them require the house to look institutional. They just require noticing before you sign.
Master-planned active adult communities generally handle this well, which is one of their genuine advantages and a reason they command a premium. Many are designed with internal golf cart or low-speed vehicle networks and put amenities within a short flat distance of the homes. Historic downtowns with genuine walkability handle it well too, but often in older housing stock with stairs. The combination that ages worst is the large-lot exurban house with beautiful views and a fifteen-minute drive to anything, which is also, reliably, the one people fall in love with.
Distance From Family and the Reverse Migration Problem
There is a well-documented pattern in retirement relocation that the city guides never mention, and it is the reason some very well-researched moves end in a second move nobody budgeted for.
The pattern goes like this. A couple retires in their mid sixties in good health and moves somewhere warm and interesting, often several states away from their adult children. For ten or fifteen years it is exactly what they wanted. Then one of them has a significant health event, or one of them dies, and the surviving spouse is suddenly alone in a place chosen for two healthy people, a long flight from anyone who could help. Within a couple of years they move again, usually back toward family, usually under time pressure, usually at considerable cost, and usually into whatever housing is available rather than what they would have chosen.
That second move is the expensive one. It happens fast, it happens during a crisis, and it happens after the first house has been furnished and settled into for a decade. Understanding that it is a common outcome, rather than a personal failure, is the point of raising it.
None of this argues against moving. It argues for asking a more specific question than the one most people ask. Not how far is family, but:
- Who would actually show up? Name the person. Not the family in aggregate, the specific individual who would get in a car at ten at night. Then measure the distance to them, not to the nearest relative in the abstract.
- How hard is the trip in both directions? A nonstop flight to a major airport is a completely different relationship than two connections plus a two-hour drive. Airport access is a legitimate retirement location criterion and it is rarely on anyone’s list.
- Can the destination absorb visitors? A guest room and reasonable proximity to something the grandchildren want to do is the difference between family visiting twice a year and twice a decade.
- What is the plan if one of us is alone? This is an unpleasant conversation and it is the single most valuable one in the whole process. Households that have it in advance make different and generally better decisions about location, housing type, and how much house to buy.
One structural option worth considering: choosing a metro that is genuinely close to family but a suburb or exurb within it that meets your cost and lifestyle criteria. It is often possible to get most of what you moved for while remaining a short drive from the person who would show up. That configuration is less romantic than the beach town four states away and it survives contact with the second half of retirement considerably better.
Coastal and Sunbelt Markets Worth Putting on Your List
What follows in the next four sections is a shortlist, not a ranking, and deliberately not a stat block. For the reasons laid out in Section 1, we are describing the structural character of each market and what specifically to check there, then leaving the current numbers to you. Run every one of these through the nine factors before it earns a visit.
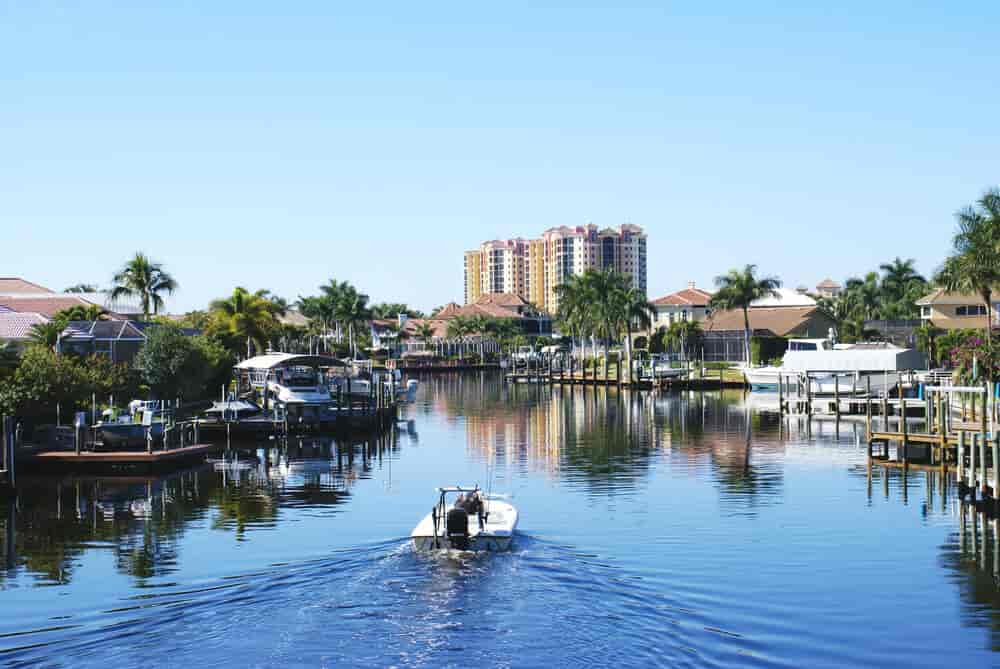
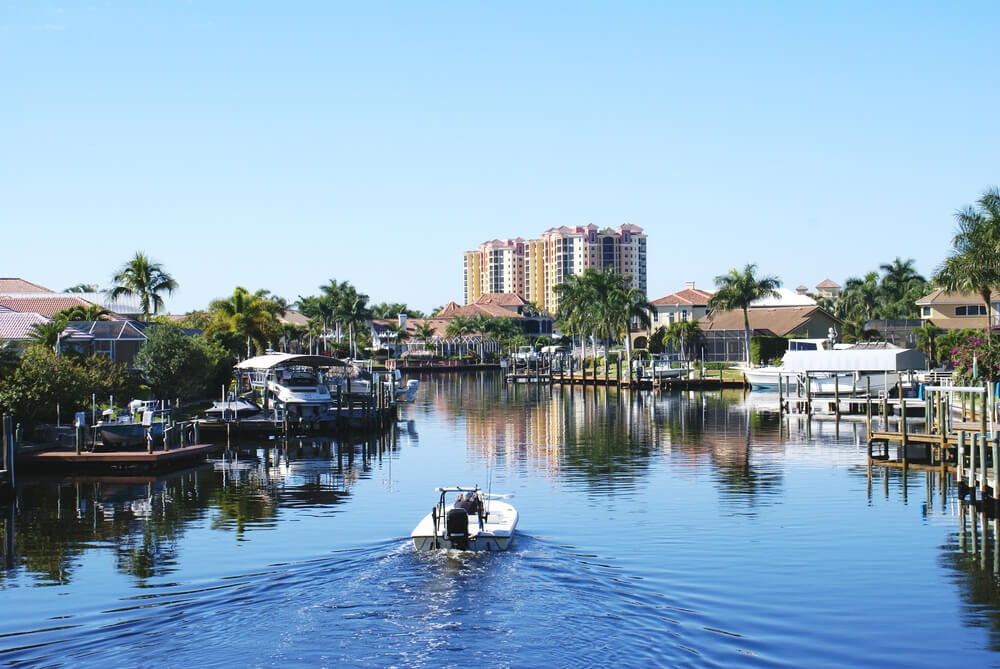
Lee County, Florida (Cape Coral, Fort Myers, North Fort Myers). Southwest Florida’s Gulf Coast remains one of the highest-volume retirement destinations in the country, with an established retiree population, a large stock of single-story housing, and no state income tax. It is also the clearest test case for Section 11. This is a hurricane-exposed coastal market with meaningful flood and wind considerations that vary street by street, and insurance is the line item that will determine whether the budget works. What to check: a real insurance quote on the actual address before making an offer, the flood determination for the specific parcel rather than the neighborhood, roof age, and whether the property carries a community development district assessment.
The Grand Strand, South Carolina (Myrtle Beach, North Myrtle Beach, Little River). A long-established retirement corridor with a lower cost basis than most of coastal Florida, a large concentration of age-restricted communities, and South Carolina’s generally favorable treatment of retirement income and owner-occupied property. Winters are mild without being tropical. The trade-offs are real seasonality, with summer traffic and service capacity that change the character of the place substantially, and the same coastal wind and flood questions as any Atlantic beach market. What to check: how far inland you need to be for the insurance math to work, and what the shoulder seasons actually feel like.
Coastal North Carolina (Wilmington, Leland, and the surrounding Brunswick County communities). This corridor has been one of the fastest-growing retirement destinations in the Southeast for a decade, and the reasons hold up: a genuine small city with a hospital system and an airport, a large supply of newer single-story and age-restricted housing inland from the beaches, and a climate with four seasons that are all usable. North Carolina does not tax Social Security. The pressures are growth-related: traffic, healthcare capacity keeping pace with in-migration, and rising prices in the most desirable pockets. What to check: new patient wait times with primary care practices, and how far the insurance picture improves as you move inland from the water.
Coastal Georgia (Richmond Hill, Savannah area). Lower profile than the Carolinas and Florida, with a similar climate, a lower cost basis, and Georgia’s retirement income exclusion for older residents. Savannah provides the urban amenities and the medical infrastructure while the surrounding communities provide the housing. Same coastal caveats apply. What to check: hurricane and flood exposure, and how the medical specialist depth looks for your specific needs, because this is a smaller market than it appears.
Central Texas (Georgetown, Round Rock, and the Hill Country). No state income tax, a large and mature active adult community sector north of Austin, and the property tax mechanics described in Section 7 that materially reduce the headline burden for homeowners past 65. The trade-off is that Texas property taxes are high before those mechanisms apply, and summers are long and hot. What to check: whether the over-65 exemption and school tax ceiling have actually been filed and recorded for the property, and what the non-school portion of the bill looks like, because the ceiling does not touch it.
Mountain and Inland West Markets Worth Putting on Your List
The interior West trades hurricane exposure for wildfire exposure, humidity for elevation, and generally offers a very different daily rhythm. It suits a particular kind of retirement extremely well and suits others poorly, and the difference is usually about how much of your life is outdoors and how well you tolerate altitude and cold.
The Grand Valley, Colorado (Grand Junction, Fruita, Palisade, Orchard Mesa). Western Colorado at a much lower cost basis than the Front Range, with a regional medical center that serves a wide area, a genuine four-season climate at moderate elevation, and immediate access to high desert and canyon country. Colorado’s treatment of Social Security for residents 65 and older is favorable, though the state does still tax some retirement income depending on age and amount, which is worth confirming for your specific situation. What to check: specialist depth, because this is a regional hub serving a large rural area rather than a major metro, and wildfire exposure for the specific parcel.
Colorado Springs, Colorado. A larger market with more medical infrastructure, strong outdoor access, and a substantial military retiree population with the VA and TRICARE infrastructure that follows. Cost of living has risen considerably and it is no longer the value proposition it was a decade ago. What to check: current housing cost against your own budget rather than against a five-year-old figure, and how elevation sits with any cardiac or pulmonary condition in the household.
Prescott and the Arizona high country. An alternative for people who want Arizona’s tax treatment and sunshine without Phoenix summers. Elevation moderates the heat substantially. What to check: wildfire risk and insurance availability, which in parts of this region is now the binding constraint rather than price, and the size of the medical market.
The Boise metro, Idaho. Rapid in-migration has changed this market considerably and prices reflect it, but the fundamentals that attracted people remain: a real city with a hospital system and an airport, four seasons at moderate elevation, and extensive outdoor access. What to check: whether growth has outpaced healthcare capacity in the specific specialties you need, and what the water and wildfire picture looks like for the specific area.
Across all of the interior West, two checks matter more than anywhere else in the country. Run every candidate through FEMA’s National Risk Index for wildfire specifically, and get an insurance quote early rather than late, because in some of these markets availability rather than price is what will decide the question.
College Towns and Medical Hub Markets Worth Putting on Your List
This category deserves its own section because it scores unusually well on the factors that matter most in the second half of a retirement, and unusually poorly on the ones people weight most heavily in the first half. University towns and regional medical hubs tend to have deep specialist coverage, teaching hospitals, continuing education programs open to older residents, cultural programming that runs year-round, and a population that turns over rather than ages in place. What they generally do not have is warm winters or low cost of living.
The Research Triangle, North Carolina (Raleigh, Durham, Cary, Clayton, Garner). Multiple major health systems including two academic medical centers, an international airport, four moderate seasons, and no state tax on Social Security. It is a large metro with the traffic and the housing cost that implies, and the outer communities are where the value is. What to check: whether the specific suburb sits in the service area of the health system and plan combination you want, and what the drive to your chosen hospital actually looks like at rush hour.
The Tri-Cities, Tennessee (Johnson City, Kingsport, Greeneville, Gray). This is one of the more underrated retirement markets in the eastern half of the country. Tennessee has no state income tax. The region has a university with a medical school and a regional health system serving a wide area, a low cost basis, and the southern Appalachian climate described in Section 14, which is arguably the most usable in the country. Elevation is moderate. What to check: specialist depth outside the core service lines, and how far you are from a larger metro if you need something the region does not have.
Columbia, South Carolina. A state capital with a university, a medical school, and a substantially lower cost of living than the South Carolina coast, plus the state’s favorable treatment of retirement income and owner-occupied property. Summers are genuinely hot and it is inland, which removes coastal insurance exposure but also removes the beach. What to check: how the summer suits you, and whether the amenity mix compensates for not being on the water.
Des Moines and the surrounding suburbs, Iowa (Urbandale, West Des Moines). A consistently well-regarded midwestern metro with strong healthcare infrastructure, a very low cost basis relative to income, and a state that does not tax Social Security and has broadened its treatment of other retirement income in recent years. Winter is the trade and it is not a small one. What to check: honestly, whether you will tolerate the winter, which is a question best answered by visiting in January rather than in June.
Southeastern Wisconsin (Waukesha, Brookfield, Pewaukee, Hartland). The suburban ring west of Milwaukee combines lake access, strong healthcare, low crime, and proximity to Madison and Chicago. Wisconsin does not tax Social Security. Same winter caveat as Iowa, with the same recommendation.
Affordable Markets Worth Putting on Your List
If the budget is the binding constraint, the honest advice is to widen the search away from the places that appear on every list, because the retirement-destination premium is real and it is entirely avoidable. The markets below are genuinely inexpensive without being isolated, which is the combination that matters.
Central Arkansas (Little Rock, North Little Rock, Sherwood, Benton, Bryant, Maumelle). A metro with a major academic medical center and a VA hospital, a very low housing cost basis, and a state that does not tax Social Security. The suburbs south and west of Little Rock offer quiet, low-cost, single-story housing within a short drive of the medical infrastructure. What to check: summer heat and humidity, and whether the cultural and social mix suits you, because this is a smaller metro than the ones on most lists.
Middle Georgia (Macon, Warner Robins area). Low cost of living, a regional medical center, Georgia’s retirement income exclusion for older residents, and easy highway access to Atlanta for anything the region does not have. What to check: specialist depth, and whether the drive to Atlanta is one you would actually make when you need to.
Upstate South Carolina (Spartanburg, Boiling Springs, Inman). Foothills of the Blue Ridge, a mild climate, a low cost basis, hospital infrastructure in Spartanburg and more in Greenville nearby, and South Carolina’s tax treatment. This corridor has quietly become one of the better value propositions in the Southeast. What to check: how quickly prices are moving, because they have been moving.
The Piedmont Triad, North Carolina (Winston-Salem, High Point, Thomasville, Clemmons). An academic medical center in Winston-Salem, a very reasonable cost basis for a market of that size, four seasons, and no state tax on Social Security. It gets substantially less attention than the Triangle or Asheville and costs considerably less than either. What to check: whether the amenity level meets your expectations, since this is a quieter market than its neighbors.
South Georgia (Valdosta) and the smaller Georgia and Alabama line markets. The lowest cost tier that still has a hospital and a college. Genuinely inexpensive. What to check: everything in Section 10, carefully, because at this end of the cost spectrum healthcare depth is the constraint that will decide whether the move works.
One caution that applies to this entire category. A very low median home price is sometimes a signal of a healthy affordable market and sometimes a signal of long-run population decline, weak labor market, and an eroding services base. Those look identical in a table and completely different in person. The distinguishing questions are whether the population is growing or shrinking, whether the hospital is expanding or consolidating service lines, and whether young families are moving in. All three are answerable in an afternoon and none of them appear in a cost-of-living index.
Popular Retirement Cities We Would Think Twice About and Why
Every list tells you where to go. Almost none tell you where the recommendation deserves a second look, which is the more useful information, because the places that appear on every list are the places where the recommendation has been copied the most times without being re-examined.
None of the four below is a bad city. Each is genuinely appealing and each has been recommended for reasons that were once correct. Each also carries a specific issue that the guides recommending it consistently omit.
Youngstown, Ohio, and the ultra-low-cost Rust Belt entries generally. These appear on retirement lists to provide an affordable counterweight to the Sunbelt entries, and the housing cost is real. Two problems. First, as covered in Section 1, the figures being quoted are frequently years out of date, which makes the market look considerably cheaper than it currently is. Second, and more importantly, extremely low housing cost in a market with long-term population decline usually correlates with thin specialist coverage, consolidating hospital service lines, and a shrinking base of the services you will need later. If you are considering this tier, do the Section 10 healthcare work first and let it decide the question, not the price.
Scottsdale, Arizona. Warm, beautiful, extremely well served, and consistently one of the most expensive markets on any retirement list, frequently well above the national cost-of-living average while sitting in an article about affordability. The heat is a genuine consideration for a full third of the year. Longer term, water allocation in the Colorado River basin is an unresolved policy question with real implications for cost and development in the region. None of that makes it a poor choice for someone whose budget accommodates it. It makes it an odd fit for a general-purpose retirement recommendation.
Daytona Beach and the lower-cost Florida coastal markets. These earn their place on lists through Florida’s tax treatment and low housing prices, which are both real. What the recommendations omit is that the low housing price is partly a function of the same exposure that drives the insurance cost, and that the insurance line item can consume the entire tax saving and more. The tax benefit is quoted; the insurance cost is not. Get the quote before you take the recommendation.
Charleston, South Carolina. Genuinely one of the most attractive small cities in the country and deserving of the attention. Three things the recommendations skip: cost of living has run well above the national average for some time, recurring tidal and rainfall flooding in parts of the historic core and surrounding low-lying areas is an ongoing infrastructure challenge rather than a rare event, and the traffic on the peninsula and its approaches is significant. If Charleston is the goal, the answer for a lot of retirees is one of the surrounding communities rather than the peninsula itself, at a fraction of the cost and with a materially better flood picture.
The general lesson is worth more than the four examples. When a city appears on every list with the same three reasons attached, those reasons have probably been copied rather than checked. Find the thing nobody is mentioning. It is usually insurance, healthcare capacity, or a cost figure that has quietly doubled.
Snowbirding, Split Residency, and Establishing Legal Domicile
A large number of retirees never make a clean move. They keep a home in the north and spend part of the year in the south, or they rent seasonally, or they spend a couple of transitional years before committing. This is a sensible approach and it comes with a set of complications that almost nothing written about retirement locations addresses.
Residency and domicile are different things. Residency is generally about physical presence and can apply in more than one state. Domicile is your one true permanent home, the place you intend to return to, and it is what determines which state can tax your income and which state’s estate rules apply at death. You can be a resident of two states and domiciled in only one.
States that lose a taxpayer sometimes look closely. High-tax states have well-developed procedures for examining whether a departure was genuine, particularly for higher-income households. The examination looks at where you actually spend your time, where your primary physician and dentist are, where your vehicles are registered, where you vote, where your professional and religious affiliations are, where your closest personal belongings are kept, and where your mail goes. Day counts matter, and the burden of proof frequently falls on the taxpayer.
Establishing a new domicile is a set of deliberate acts, not a feeling. The common list includes obtaining a driver’s license in the new state, registering vehicles there, registering to vote and actually voting there, filing a declaration of domicile where the state offers one, claiming the homestead exemption on the new property and relinquishing it on the old, updating estate documents to the new state’s law, moving primary banking and professional relationships, and changing the address on file with Social Security, Medicare, and every financial institution.
Health coverage has its own residency rules, and they do not necessarily align with tax residency. Medicare Advantage and Part D plans have service-area residency requirements, and spending long periods outside the service area can create problems. If a genuinely split year is the plan, Original Medicare plus a Medigap policy is the arrangement that generally handles it more gracefully, which loops directly back to the underwriting timing question in Section 9. Raise it with a SHIP counselor before you build a plan around six months in each place.
Two homes means two of everything. Two insurance policies, two utility accounts, two sets of maintenance, two property tax bills, and a vacancy problem at each end for half the year. Insurers care about unoccupied periods and some policies have conditions attached. Read them.
The specific advice on all of this belongs with a tax professional and, where domicile is contested or estate planning is involved, an attorney. What we would add is a practical note: households that snowbird for two or three seasons before committing consistently report making better final decisions than households that sold and bought in one step. Renting in your target market through a full year, including the season nobody visits in, is the single most informative thing you can do.
How to Test Drive a City Before You Commit to It
Almost everyone who moves for retirement visits first. Almost everyone visits wrong. A vacation and a life are different experiences of the same place, and the vacation version is engineered to be flattering.
A test drive that actually produces information looks like this:
- Go in the worst season, not the best one. If it is a Gulf Coast market, go in August. If it is a northern market, go in February. If it is a mountain market, go during wildfire season. You already know what the good season feels like, that is why the place is on your list. The question is whether the bad season is survivable.
- Rent in the actual neighborhood, not in a resort or hotel district. A month if you can manage it, two weeks at minimum. Stay where the housing you would buy is, and do it without a rental car for at least a couple of days to see what Section 15 actually feels like there.
- Do your ordinary week. Groceries at the store you would use. A haircut. The pharmacy. The library. Church or a club or whatever your version of that is. The purpose is not to enjoy yourself, it is to find out whether the ordinary week is pleasant, because the ordinary week is what you are actually buying.
- Make the healthcare calls while you are there. Three primary care practices, and a specialist in whatever discipline matters to your household. Ask about new patient availability. Ten minutes, and it will tell you more than the rest of the trip.
- Get one real insurance quote. Pick an actual listing in the neighborhood you like, in the price range you are considering, and get a quote on that address. Not a state average. That address.
- Drive the route to the hospital at rush hour, and then drive it at two in the morning. Both numbers matter for different reasons.
- Talk to people who moved there five years ago, not to people who moved there last year. The recent arrivals are still in the honeymoon. The five-year cohort will tell you what they wish they had known, and they are usually happy to.
- Sit in on a homeowners association meeting if you are considering a community with one. They are frequently open. An hour in that room tells you more about the community than any tour.
Two additional things worth doing before you go. Run the address through FEMA’s National Risk Index, and pull the county assessor’s page for a few comparable properties to see what the actual tax bills look like rather than what the listing estimates. Both are free and both are more predictive than anything you will see on the trip.
If you are relocating in stages and need to hire help for the move itself, our guide to hiring movers covers how to compare estimates and avoid the common problems, which are worse on long-distance moves than local ones.
The Downsizing Arithmetic: What Actually Fits in a Retirement Home
This is the section no competing guide publishes, and it is the one that decides whether the first six months in the new place are pleasant or miserable. Everyone downsizing compares square footage. Square footage is the wrong measure, and comparing it is why so many people arrive at a new house with a garage they cannot park in.
Living space compresses gracefully. Storage space does not. A household that moves from 2,400 square feet to 1,600 square feet loses a third of its floor area, which sounds manageable and usually is. What actually breaks the move is the other reduction, the one nobody counts: the full basement, the floored attic, the two-car garage, and the four closets that do not exist in the new house. That is where most of a long-tenured household’s possessions actually live, and in a typical single-story retirement home a large share of it simply has nowhere to go.
Run the arithmetic properly. Instead of comparing living area, do this:
- Inventory the non-living storage in the current house. Basement, attic, garage, shed, and any closet that holds things rather than clothes. Estimate each in cubic feet: floor area multiplied by the height you actually stack to. A two-car garage with eight feet of usable height is on the order of 3,000 cubic feet gross, and even at half occupancy that is a lot of belongings.
- Inventory the same categories in the new house. Usually a one-car or two-car garage, a coat closet, a linen closet, and no basement or attic. Frequently a tenth to a third of what you had.
- The difference is the number you have to solve. Not the square footage difference. This one. And it is usually several times larger than people expect.
Once you have that number, there are only four things you can do with it: sell, donate, give to family, or store. Most households do all four, and the mistake is doing them in the wrong order and on the wrong timeline. The sequence that works looks like this:
- Start twelve months out, not two. Selling furniture and giving heirlooms to family both take far longer than expected, and both go badly under time pressure. Compressed timelines are how good furniture ends up on the curb.
- Handle the emotionally difficult categories first, while there is still time to be thoughtful. Photographs, letters, inherited furniture, and anything belonging to someone who has died. These are the categories where a deadline produces regret.
- Do the easy volume last. Garage, tools, holiday decorations, and duplicate kitchen items are fast decisions and should not be consuming the calendar early.
- Deal with the adult children’s belongings explicitly. In a very large share of downsizing moves, a meaningful fraction of what is in the basement and attic belongs to children who moved out decades ago. Give a real deadline and a real consequence, kindly and early.
For the portion that genuinely does need to go somewhere, here is honest sizing guidance rather than a sales pitch. A unit roughly 10 feet by 10 feet holds on the order of the contents of a one to two bedroom apartment when packed properly, which in a downsizing context is usually enough for the overflow from a garage plus a few pieces of furniture. Something in the 10 by 15 range covers a larger overflow including several rooms of furniture. A 10 by 20 is a full household and is more than most downsizing moves actually need. The most common sizing error is renting too large a unit early, filling it because it is there, and then paying for the extra space for years. If you are between two sizes, the smaller one and a stricter sort is almost always the better financial decision.
If you want to run the numbers against actual availability, you can browse available units by size across our locations. We rent month to month with no long-term contract, and everything is done online, which matters more than it sounds during a move where you are already coordinating a closing, a moving company, and a Medicare enrollment window.
One product note in the interest of accuracy, since retirement moves often involve furniture, artwork, and documents that people care about. Our climate-controlled units are temperature-regulated, meaning they hold the space within a moderated temperature range rather than exposing your belongings to seasonal extremes. They do not manage moisture, and anyone who tells you a storage unit will is overselling. If you are storing something genuinely irreplaceable, pack it properly, use appropriate containers, and understand what temperature regulation does and does not cover. Availability of temperature-regulated units varies by property, so confirm it for the specific location you are considering rather than assuming.
When Storage Makes Sense in a Retirement Move and When It Does Not
We rent storage units. We would still rather you not rent one you do not need, because the version of this that goes wrong is genuinely bad for people and we see it.
Storage makes sense in a retirement move when:
- The timing does not line up. You have closed on the sale and the new place is not ready, or you are moving in stages. This is the clearest case and it is usually a matter of weeks or a few months.
- You are renting first to test the market. Section 22 makes the case for renting in a destination before buying. A rental is almost always smaller than what you will eventually buy, and holding the difference for a defined period while you make a good decision is a reasonable use of money.
- You are staging the house for sale. Clearing furniture and personal items out during a listing period is standard practice and it is a short, bounded use with a specific end date.
- An estate is unsettled. When belongings are subject to a probate process or being divided among family who are not all in the same place, a temporary hold while that resolves is legitimate and often the least painful option.
- You are keeping a vehicle you are not ready to give up. An RV, a boat, or a project car frequently does not fit at a community with covenants restricting what can be parked in a driveway. Vehicle and RV storage solves a specific problem cleanly.
Storage does not make sense, and we will say so:
- When it is a way of not making the decision. This is the most common failure and it is the one that costs the most. If the honest reason for the unit is that sorting through it was hard and the move was coming, the unit does not solve that. It defers it at a monthly cost, and in our experience it is deferred for years rather than months. Do the sort. It is unpleasant for a weekend and then it is done.
- When the monthly cost is a meaningful share of a fixed income and the contents are replaceable. Run the arithmetic without sentiment. If the unit costs a hundred and change a month, that is over $1,200 a year and over $6,000 across five years. Ask honestly whether the contents would cost that to replace. For a garage full of tools, holiday decorations, and furniture from a house you no longer live in, the answer is very often no. On a fixed income this is a real number.
- When it is holding things nobody has asked for. If the contents are being kept for adult children who have not asked for them and do not have room for them, that is worth a direct conversation now rather than a decision your executor makes later. Storing possessions on behalf of people who do not want them is one of the more common and least discussed patterns in this industry.
- When there is no end date. A unit rented for a defined purpose with a defined end is a tool. A unit rented indefinitely with a vague intention to sort it out becomes a recurring bill that outlives the reason for it. If you cannot name the month you intend to empty it, that is a signal worth listening to.
- When downsizing further would solve it. Sometimes the honest answer is that the new house is too small for the life you actually want, and paying monthly to bridge that gap for years is more expensive than buying differently. That is a housing decision, not a storage decision, and no storage company should be helping you avoid it.
The general rule we would give anyone: rent for a reason with a date attached, size it to what you have actually decided to keep rather than to what you have not yet sorted, and revisit it at six months. If you are renewing at eighteen months for a unit you took for a three-month gap, something in the plan needs a look.
Frequently Asked Questions About Retiring in the US
Health coverage continuity, because it is the only factor where a wrong decision can be difficult to reverse. Taxes can be planned around, housing can be changed, and climate can be adapted to. If a move leaves you unable to obtain the Medicare supplement coverage you wanted, moving back does not fix it. Work out the health coverage question before choosing a house.
The large majority of states do not. As of the most recent tax year, published lists commonly identify around eight states that still tax some Social Security income, and most of those exempt lower and middle income retirees through thresholds or age rules. The list has been shrinking as states phase these taxes out, and published summaries frequently lag the legislation. Confirm the current position with the revenue department of any state you are considering.
Original Medicare, meaning Part A and Part B, works anywhere in the country that accepts Medicare. Medicare Advantage and Part D prescription plans are sold by service area, usually at the county level, so moving generally means changing plans. Moving out of a plan’s service area triggers a Special Enrollment Period with a defined window. Contact your State Health Insurance Assistance Program for free guidance specific to your situation.
Generally no. Relocating is not by itself a federal guaranteed issue right for Medicare supplement coverage. Outside your one-time six-month Medigap Open Enrollment Period, insurers in most states may medically underwrite your application. Some states provide additional protections beyond the federal minimum. This is worth discussing with a SHIP counselor before you commit to a destination, because it is one of the few retirement decisions that can be hard to undo.
Under federal regulations implementing the Housing for Older Persons Act, a community claiming the 55 and older exemption must have at least one person aged 55 or older living in at least 80 percent of its occupied units. It must also publish policies demonstrating that intent and verify occupancy on a regular cycle. The remaining 20 percent of units are not required to include anyone 55 or older.
Not necessarily. Communities operating under the 62 and older exemption are intended for and occupied solely by people 62 or older, and HUD’s regulations indicate such a community could refuse an applicant who is 62 if their spouse is under 62. Communities under the 55 and older exemption work differently. Ask which exemption a community operates under, in writing, before proceeding.
Federal law does not set a minimum age for the other occupants of a qualifying unit. What restricts children in most active adult communities is the community’s own recorded governing documents, not federal law. Those documents vary and they are what you should read.
Within the same state, sometimes. Across state lines, essentially never. Florida allows accumulated Save Our Homes benefit to transfer to a new Florida homestead within a filing window, and Texas allows an over-65 school tax ceiling to carry to another Texas home with a certificate from the former appraisal district. Neither crosses a state line. If you have held a home a long time under a cap or freeze, quantify what you are giving up before comparing payments.
Not automatically. States without an income tax generally raise revenue through property and sales taxes instead, and for a homeowner the property tax bill can exceed what a modest income tax would have cost. The comparison that matters is your total bill, run against your actual income and an actual property in the actual taxing jurisdiction, not a comparison of headline rates.
Published state averages vary widely depending on methodology, and for coastal markets the range between sources is large enough that the averages are not useful for planning. Premiums are set by the specific address, construction, roof age, and distance to water, and flood coverage is a separate policy in every case. Get a quote on the actual property before making an offer.
About twelve months for a full-house downsizing move. Selling furniture, distributing heirlooms to family, and working through the emotionally difficult categories all take considerably longer than expected, and compressing them creates decisions people regret. The easy volume in the garage can wait until the end.
It depends on what you have decided to keep, which is why the sorting should come first. As a rough guide, a unit around 10 feet by 10 feet holds roughly the contents of a one to two bedroom apartment when packed well, and a 10 by 15 covers a larger overflow including several rooms of furniture. Most downsizing households need less than they initially estimate. If you are between sizes, the smaller unit plus a stricter sort is usually the better decision.
Before, if the timing gap is the reason you need one, since the unit needs to exist on moving day. Renting a unit after you arrive because things did not fit is usually a signal that the sorting was incomplete rather than that more space is required. Either way, rent for a defined period with an end date in mind.
Renting first in the destination for a full year, including the season nobody visits in, consistently produces better final decisions than buying immediately. It costs money and it delays the move, and it also prevents the far more expensive mistake of buying in a market you have only experienced on vacation.
Planning Your Retirement Move
The best place to retire is not a city that appears on a list. It is the specific address where the coverage works, the tax picture holds up, the insurance is obtainable, the healthcare is reachable, the house still functions when you are no longer driving, and someone who loves you is close enough to come over. Run your candidates through the nine factors in Section 2 and you will end up with a shortlist that looks nothing like the one you started with, and a considerably better decision.
Do the health coverage work first, the insurance quote second, and the house tour last. That ordering feels backwards and it is the one that prevents the expensive mistakes.
When the moving part arrives, we can help with that piece. 10 Federal Storage operates facilities across the Southeast, Texas, the Midwest, and the Mountain West, including markets that show up on a lot of retirement shortlists. Every unit rents online in a few minutes with no office visit and no long-term contract, which is genuinely useful during a stretch when you are already coordinating a closing, a moving company, and an enrollment deadline.
Find a storage unit near your destination or read more about how renting with 10 Federal works. More planning guides are on the 10 Federal Storage blog.
About the Author
10 Federal Storage
Our team at 10 Federal Storage has been in the self storage industry for decades. With knowledge gained from multiple universities and in the field, we are well-prepared and excited to assist with your storage needs. When you rent a unit with us, you can feel confident that our seasoned customer service team’s help will make your transition as seamless as possible. Customer satisfaction is our number one priority, and we strive to make your experience exceptional with our automated leasing options, diverse unit sizes, and a strong commitment to sustainability.