Most Affordable States to Live In: A State-by-State Guide
by 10 Federal Storage
Published on October 7, 2026
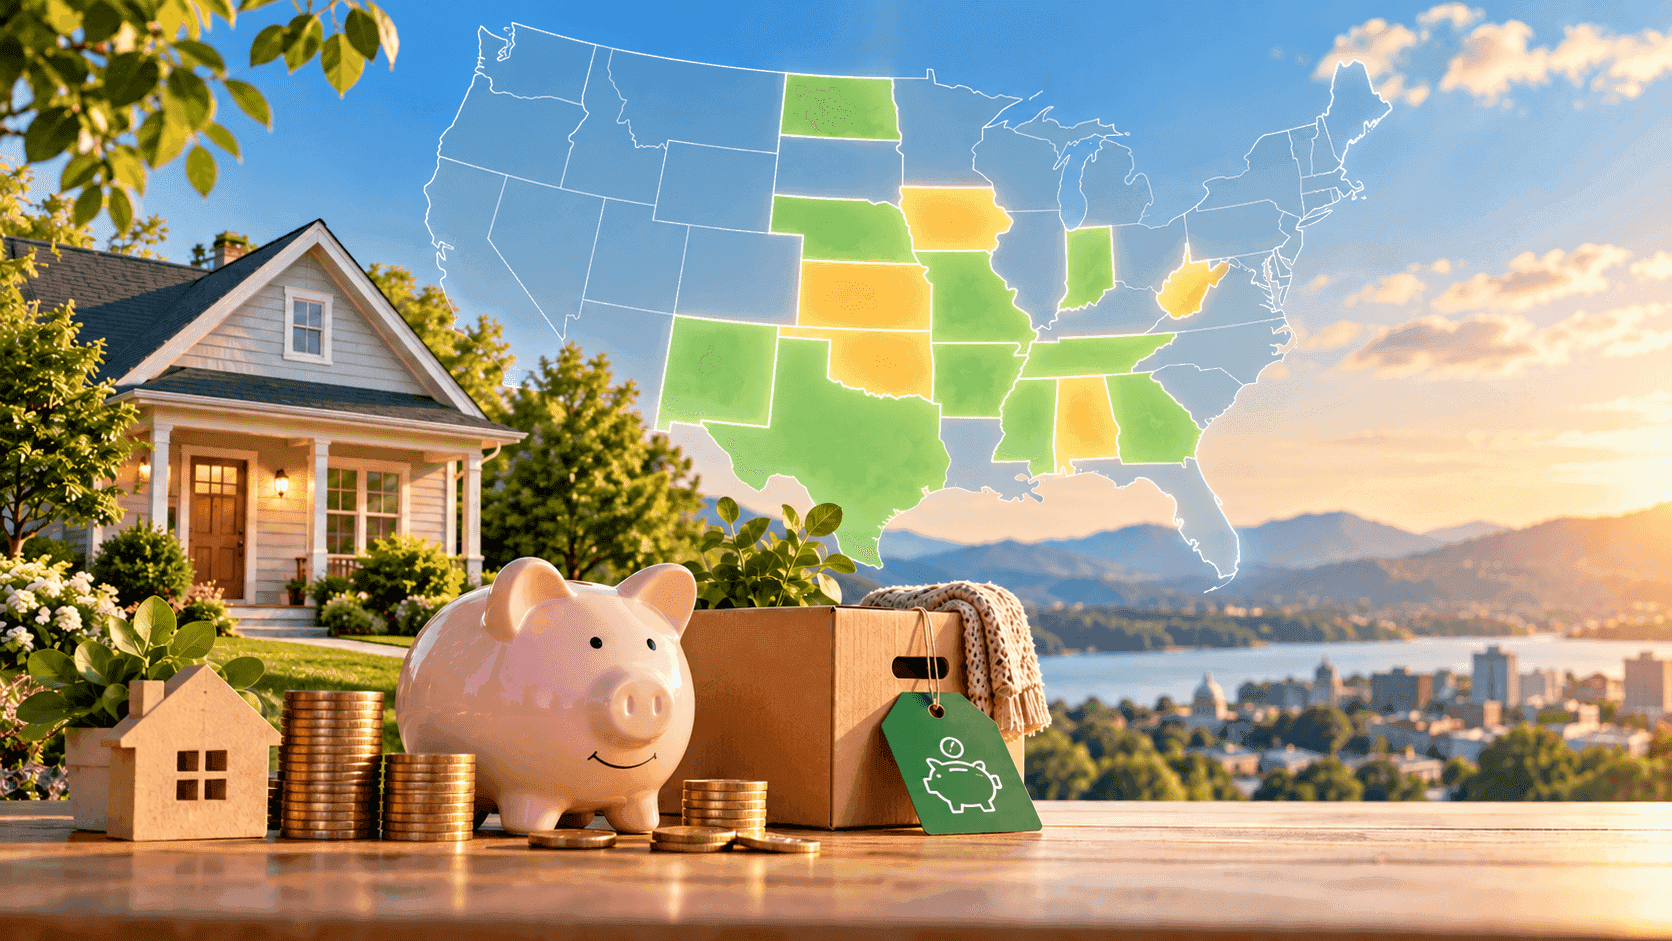
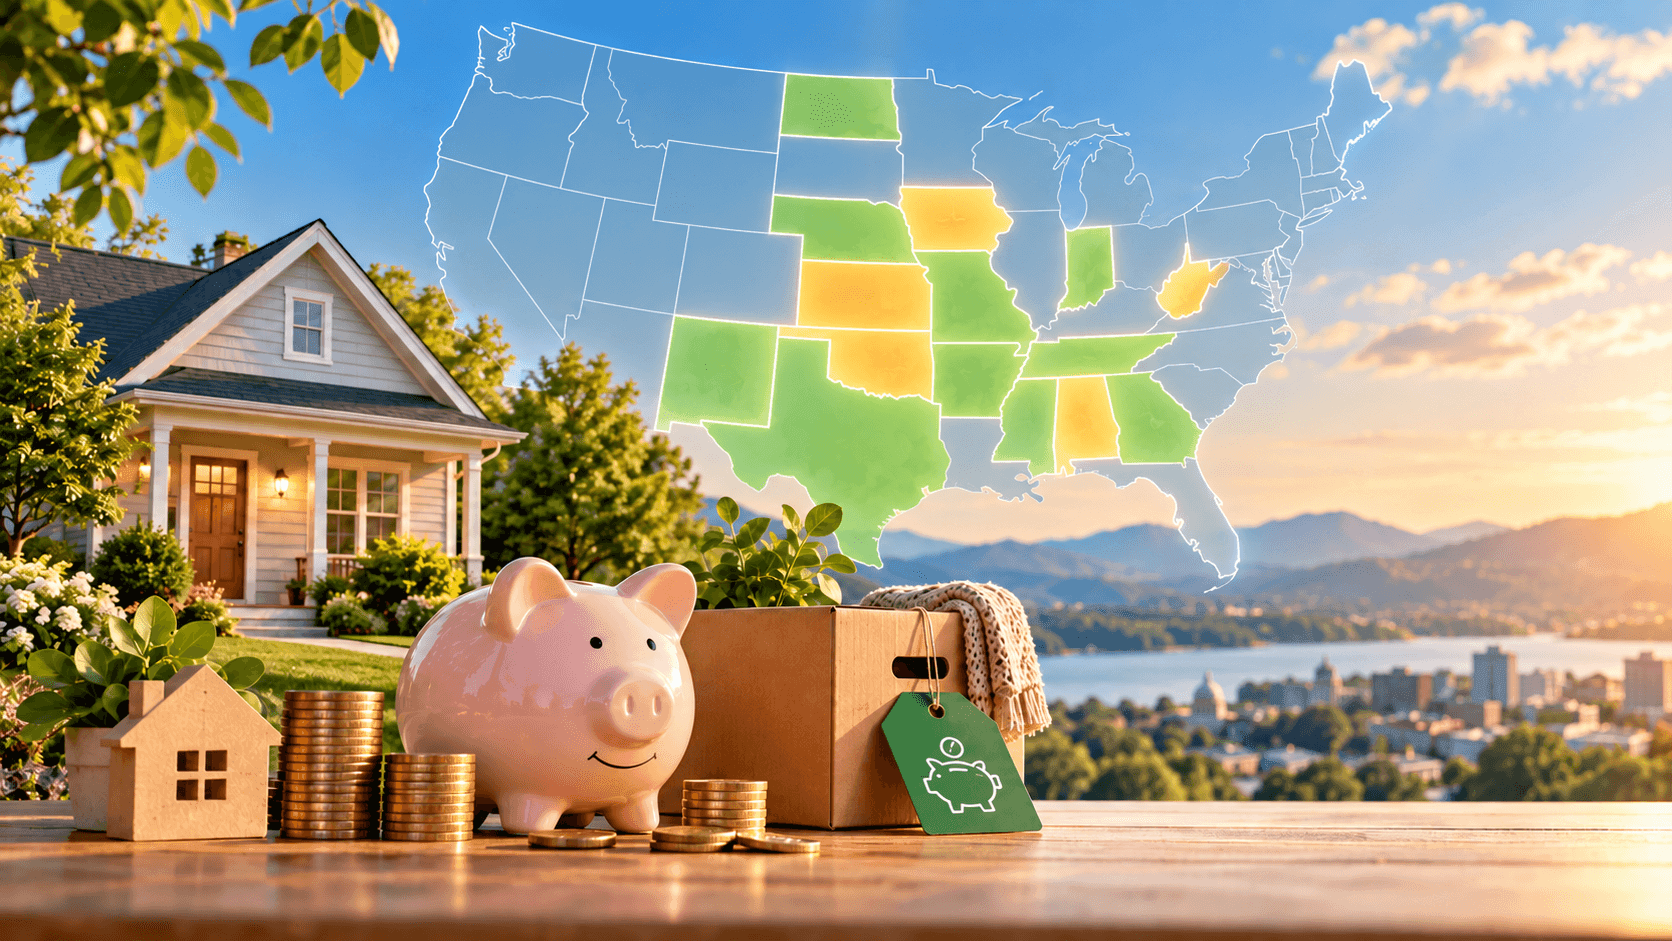
The most affordable states to live in are concentrated in the South and the Midwest. On the latest state-level cost of living data, from the second quarter of 2026, Oklahoma has the lowest prices in the country, followed by Alabama, Iowa, West Virginia, and Kansas. In the cheapest of them, housing runs roughly a third below the national average, and every one of the 15 lowest-cost states sits at least 9 percent below average overall.
This guide profiles those 15 states one by one: what makes each one affordable, its main cities, who it suits best, and the trade-offs worth knowing before you move. Every profile uses the same public data so the states compare fairly: the Cost of Living Index from the Council for Community and Economic Research (C2ER), as published by the Missouri Economic Research and Information Center (MERIC); the federal government’s regional price parities; Census Bureau income figures; Tax Foundation tax burden estimates; and the Energy Information Administration’s average electric bills.
After the profiles, you will find the cheapest states by region, the full 50-state ranking, and a closer look at the costs that separate one affordable state from another for a real household: taxes, homeowners insurance, electric bills, and incomes. The guide ends with what a move to a cheaper state costs and how long it takes to pay for itself.
We are a self storage company, and we operate in several of the states on this list and in none of the others. The ranking below is built entirely from public data and treats every state the same way. You will also find a frank section on when moving to a cheaper state does not save money, and another on when you do not need storage for the move at all.
Table of Contents
- The Short Answer: The Cheapest States to Live In
- The Five Lowest-Cost States: Oklahoma, Alabama, Iowa, West Virginia, and Kansas
- Ranks 6 Through 10: Mississippi, Missouri, Arkansas, Indiana, and Tennessee
- Ranks 11 Through 15: Georgia, Nebraska, New Mexico, North Dakota, and Texas
- Just Outside the Top 15: Louisiana, Michigan, South Carolina, Ohio, and South Dakota
- The Most Affordable States by Region
- All 50 States Ranked by Cost of Living Index
- The Most Expensive States, for Context
- How These States Were Ranked
- Taxes in the Most Affordable States
- Homeowners Insurance in the Most Affordable States
- Electric Bills in the Most Affordable States
- Health Care and Transportation Costs in the Most Affordable States
- Incomes in the Most Affordable States
- The Cheapest Places Within the Most Affordable States
- What It Costs to Move to a Cheaper State
- A Worked Example: When a Move Pays for Itself
- Who Gains the Most From a Low-Cost State
- When Moving to a Cheaper State Does Not Save You Money
- How to Check the Numbers for a Specific City
- Where 10 Federal Storage Operates Among the Lower-Cost States
- Sizing Storage for a Move to a Lower-Cost State
- When You Do Not Need a Storage Unit for This Move
- Frequently Asked Questions About the Most Affordable States
- The Bottom Line
The Short Answer: The Cheapest States to Live In
On the most widely used state cost of living measure, the ten cheapest states in the second quarter of 2026 were Oklahoma, Alabama, Iowa, West Virginia, Kansas, Mississippi, Missouri, Arkansas, Indiana, and Tennessee. A score of 100 is the national average, so a score of 83 means prices about 17 percent below average for the household the index is built around.
- Oklahoma: 83.0, with the lowest housing component of any state (65.1)
- Alabama: 86.0
- Iowa: 86.1
- West Virginia: 87.0
- Kansas: 87.1
- Mississippi: 87.4
- Missouri: 88.2
- Arkansas: 89.0
- Indiana: 89.7
- Tennessee: 89.7
Source: MERIC Cost of Living Data Series, second quarter 2026, derived from the C2ER Cost of Living Index. Georgia and Nebraska (both 90.1), New Mexico (90.2), North Dakota (90.5), and Texas (90.8) round out the top 15.
The federal government’s own price measure confirms the picture. In the Bureau of Economic Analysis regional price parities for 2024, released in February 2026, the four states with the lowest overall price levels were Arkansas (86.9), Mississippi (87.0), Iowa (87.8), and Oklahoma (87.8), all of which are also in the top eight above. When a state is cheap on both measures, you can be confident it really is.
The profiles below take each of the 15 cheapest states in turn, starting with the five lowest-cost states in the country.
The Five Lowest-Cost States: Oklahoma, Alabama, Iowa, West Virginia, and Kansas
Each profile below uses the same sources so the states can be compared fairly: the MERIC/C2ER index for the second quarter of 2026, the BEA’s 2024 regional price parity where it helps, the Census Bureau’s 2020–2024 American Community Survey for household income, the Tax Foundation’s most recent state-local tax burden study (calendar year 2022, rank 1 being the lowest burden), and the Energy Information Administration’s 2024 average monthly residential electric bill. The national average electric bill in that EIA table was $142.26, and the national median household income in the same Census series was about $80,700.
1. Oklahoma
- Cost of living index: 83.0, the lowest of any state
- Main cities: Oklahoma City, Tulsa, Norman, Broken Arrow, and Lawton
- Best fit: buyers and renters who want the lowest housing costs in the country, and households that drive a lot
- Housing component: 65.1, also the lowest of any state
- BEA price parity (2024): 87.8
- Median household income: $65,039
- Median home value / median gross rent: $199,800 / $1,014
- State-local tax burden: 9.0 percent of income, 10th lowest
- Average electric bill: $132.05 a month
Oklahoma’s lead is driven by housing and transportation. Its transportation component (83.9) is the lowest in the country, and its housing component is about a third below average. Because C2ER’s state figure is an average of its participating cities, Oklahoma’s score reflects prices in its urban markets, including the Oklahoma City and Tulsa areas, rather than its small towns.
The catch is homeowners insurance, which none of the price indexes capture well. Oklahoma consistently appears among the most expensive states for homeowners premiums in quote-based estimates, reflecting its exposure to severe storms. Adjusted for local prices using the BEA parity, Oklahoma’s median household income works out to roughly $74,100 in national-average terms, still about 8 percent below the U.S. median. Cheap housing does a lot of work here, but it does not fully close the income gap.
2. Alabama
- Cost of living index: 86.0
- Main cities: Birmingham, Huntsville, Montgomery, Mobile, and Tuscaloosa
- Best fit: buyers who want low home prices and households that use a lot of health care, as long as they budget for high summer electric bills
- Housing component: 68.6
- Health care component: 85.2, second lowest in the country
- Median household income: $63,999
- State-local tax burden: 9.8 percent, 20th lowest, though only $4,585 per person in dollar terms
- Average electric bill: $173.50 a month
Alabama is cheap on housing and health care, and its per-person tax bill is among the smallest in the country in dollar terms. Its tax burden ranks in the middle because the Tax Foundation measures taxes as a share of income, and Alabama incomes are lower.
The surprise is electricity. In the EIA’s 2024 data, Alabama households paid an average of $173.50 a month, the third-highest residential bill in the country behind Hawaii and Connecticut, and more than households in California ($160.86). The reason is consumption, not price: Alabama households used an average of 1,143 kilowatt-hours a month, compared with 503 in California and 863 nationally. Long cooling seasons, and electric heating in many homes, push usage up. The C2ER utilities component (94.1) does not reflect this, because it prices energy for a standard home rather than measuring what local households actually use.
3. Iowa
- Cost of living index: 86.1
- Main cities: Des Moines, Cedar Rapids, Davenport, Sioux City, and Iowa City
- Best fit: households that want low prices without giving up income, including families and people taking local jobs
- Utilities component: 81.7, among the lowest in the country
- BEA price parity (2024): 87.8
- Median household income: $75,059
- Median home value / median gross rent: $208,000 / $972
- State-local tax burden: 11.2 percent, 34th lowest (calendar year 2022)
- Average electric bill: $111.54 a month
Iowa is the state that most clearly beats its reputation. Its prices are among the lowest in the country on both the C2ER and BEA measures, and its incomes are relatively high for a low-cost state. Adjusted for local prices, Iowa’s median household income works out to roughly $85,500 in national-average terms, about 6 percent above the U.S. median. That is unusual among the cheapest states. Most of the others that can be checked this way remain below the national median even after the adjustment.
Two cautions. Iowa’s tax burden ranked in the bottom half of states in the Tax Foundation’s 2022 study, although the state has since moved to a single flat income tax rate, so its current position is likely better than that figure suggests. And the electric bill figure does not include natural gas or propane, which many Iowa homes use for heat through long winters. Ask for a full year of utility history on any home you consider.
4. West Virginia
- Cost of living index: 87.0
- Main cities: Charleston, Huntington, Morgantown, Parkersburg, and Wheeling
- Best fit: renters, retirees, and remote workers whose income does not depend on the local job market
- Housing component: 69.9
- BEA housing rents parity (2024): 54.2, the lowest of any state
- Median household income: $59,608
- State-local tax burden: 9.8 percent, 22nd lowest
- Average electric bill: $154.76 a month
By the federal measure, West Virginia has the cheapest rents in the country, at roughly 46 percent below the national level. That makes it one of the strongest options on this list for renters and for buyers who want the lowest possible purchase price.
Its other components are less dramatic. Transportation (97.7) is close to the national average, which matters in a mountainous, largely rural state where driving distances can be long. The average electric bill runs above the national figure. And household incomes are among the lowest in the country, so the state works best for people bringing income with them, such as retirees and remote workers, rather than people relying on the local job market.
5. Kansas
- Cost of living index: 87.1
- Main cities: Wichita, Overland Park, Kansas City, Olathe, Topeka, and Lawrence
- Best fit: commuters and households with solid incomes who are comfortable with a higher tax bill
- Transportation component: 84.4, second lowest in the country
- Housing component: 78.7
- Median household income: $74,275
- State-local tax burden: 11.2 percent, 33rd lowest (calendar year 2022)
- Average electric bill: $123.90 a month
Kansas reaches the top five differently from its neighbors. Its housing component is noticeably higher than the four states ahead of it, but it is cheap almost everywhere else: transportation, miscellaneous goods and services (88.9), and health care (89.4) are all well below average. Incomes are comparatively solid for a low-cost state.
The trade-off is taxes. Kansas ranked in the bottom half of states on the Tax Foundation’s 2022 burden study, at a level identical to Iowa’s. Because the cost of living index excludes taxes, Kansas may feel less inexpensive than its rank suggests to a household paying income and property taxes there. Part of the Kansas City metro sits in Kansas, so if you are weighing that area, compare specific suburbs on both sides of the state line rather than relying on either state’s average.
Ranks 6 Through 10: Mississippi, Missouri, Arkansas, Indiana, and Tennessee
The next five states are separated by just 2.3 points, so the choice among them comes down to the details: where each is cheapest, what each does well, and what each costs that the index does not show.
6. Mississippi
- Cost of living index: 87.4 (third in the first quarter of 2026, sixth in the second)
- Main cities: Jackson, Gulfport, Biloxi, Hattiesburg, Southaven, and Tupelo
- Best fit: retirees and others living on a fixed income, who get the full benefit of some of the lowest prices in the country
- Health care component: 84.8, the lowest in the country
- BEA price parity (2024): 87.0, second lowest of any state
- Median household income: $56,447, the lowest among the states profiled here
- State-local tax burden: 9.8 percent, 21st lowest
- Average electric bill: $154.83 a month
Mississippi has some of the lowest prices in the country by any measure. The federal measure ranks it second cheapest of all states, it has the lowest health care costs on the index, and its housing component is about 29 percent below the national average. Its move from third to sixth between the first and second quarters of 2026 reflects normal survey variation more than any real change in prices.
What has not changed is the income side. Adjusted for local prices, Mississippi’s median household income works out to roughly $64,900 in national-average terms, about 20 percent below the U.S. median. That is the widest gap of any state profiled here. Mississippi stretches a fixed income further than almost anywhere, but a household that will depend on local wages should look closely at pay in its field before assuming the low prices will carry the budget. Electric bills, at $154.83 on average, also run above the national figure for the same reason as in Alabama: high consumption in a long cooling season.
7. Missouri
- Cost of living index: 88.2
- Main cities: Kansas City, St. Louis, Springfield, Columbia, Jefferson City, and Joplin
- Best fit: households earning a local wage who want low costs in every major city, not just in small towns
- Transportation component: 85.3
- BEA price parity (2024): 90.8 statewide; 92.6 in metro areas and 83.9 outside them
- Median household income: $70,702
- State-local tax burden: 9.3 percent, 13th lowest
- Average electric bill: $129.18 a month
Missouri is unusually well documented, because MERIC, the agency that publishes the state table, is part of Missouri state government and also reports a figure for each participating Missouri city. In the second quarter of 2026, every participating Missouri city came in below the national average: Joplin at 83.8, the Kansas City area at 86.6, Columbia at 89.4, St. Louis at 89.8, and Springfield at 91.6. That kind of consistency across cities is a better signal than the state’s rank alone.
The BEA data shows the other half of the picture. Missouri’s rural areas have a price level of 83.9, nearly nine points below its metro areas. Adjusted for statewide prices, Missouri’s median household income works out to roughly $77,900, about 4 percent below the U.S. median, which puts it among the better-balanced states on this list for households earning a local wage.
8. Arkansas
- Cost of living index: 89.0
- Main cities: Little Rock, Fayetteville, Springdale, Rogers, Bentonville, Fort Smith, and Jonesboro
- Best fit: buyers open to small cities, towns, and rural areas, where Arkansas has the lowest overall price level of any state
- BEA price parity (2024): 86.9, the lowest of any state
- Utilities component: 98.7, the highest among the ten cheapest states
- Health care component: 85.5
- Median household income: $60,773
- State-local tax burden: 10.2 percent, 26th lowest (calendar year 2022)
- Average electric bill: $129.13 a month
Arkansas has the lowest overall price level of any state on the federal measure, which covers the whole state, including its many small towns and rural counties. Its cities are inexpensive too, which puts it eighth on the C2ER index, but the deepest savings are outside the metros. Northwest Arkansas, home to several of the state’s largest employers, has grown quickly, and Little Rock remains the state’s largest metro.
Arkansas’s tax picture has also changed since the Tax Foundation’s 2022 study. The Tax Foundation reports that Arkansas cut its top individual income tax rate again in 2026, the fourth reduction in four years, so the state’s current burden is likely lower than its 2022 rank. Adjusted for local prices, the state’s median household income is roughly $69,900, about 13 percent below the U.S. median.
9. Indiana
- Cost of living index: 89.7
- Main cities: Indianapolis, Fort Wayne, Evansville, South Bend, and Carmel
- Best fit: households whose biggest expense is rent or a mortgage
- Housing component: 77.5
- Transportation component: 98.1
- Median household income: $71,957
- State-local tax burden: 9.3 percent, 14th lowest
- Average electric bill: $133.06 a month
Indiana’s cost advantage is almost entirely housing. Its grocery (98.2) and transportation (98.1) components sit close to the national average, so the savings show up mainly in rent or a mortgage. That makes Indiana a better fit for households whose biggest expense is housing, which is most of them, than for households whose costs are concentrated in driving or day-to-day goods.
Indiana pairs those prices with solid household incomes and a tax burden that ranked in the lowest third of states in 2022. It does not post any single dramatic number, which is why it tends to sit in the middle of rankings, but it has fewer weak spots than several states ranked above it.
10. Tennessee
- Cost of living index: 89.7
- Main cities: Nashville, Memphis, Knoxville, Chattanooga, Clarksville, and the Tri-Cities (Johnson City, Kingsport, and Bristol)
- Best fit: working households and high earners who benefit from no tax on wages
- Utilities component: 88.0
- BEA price parity (2024): 91.9
- Median household income: $69,595
- State-local tax burden: 7.6 percent, third lowest in the country
- Average electric bill: $143.32 a month
Tennessee is the only state in the top ten that does not tax wage income, and it had the third-lowest state-local tax burden in the country in the Tax Foundation’s 2022 study. Because the C2ER index leaves taxes out, Tennessee is probably more affordable for a working household than its tenth-place rank suggests.
The state relies heavily on sales taxes instead, and its combined state and local sales tax rates are among the highest in the country, so the savings are largest for households that earn a lot relative to what they spend on taxable goods. Prices also vary considerably by region: the Nashville area is the state’s most expensive market by most measures, while other parts of the state are much cheaper. Adjusted for statewide prices, Tennessee’s median household income is roughly $75,700, about 6 percent below the U.S. median.
Ranks 11 Through 15: Georgia, Nebraska, New Mexico, North Dakota, and Texas
These five states sit between 90.1 and 90.8 on the index, close enough that their order matters less than their character. They include the biggest state on the list, the only Western state in the top 15, and two Plains states with very different tax pictures.
11. Georgia
- Cost of living index: 90.1 (tied with Nebraska)
- Main cities: Atlanta, Augusta, Columbus, Macon, Savannah, and Athens
- Best fit: people who want access to a major job market while living below the national cost of living, especially outside the Atlanta core
- Housing component: 77.6
- Health care component: 100.2
- Median household income: $77,353
- State-local tax burden: 8.9 percent, 8th lowest
- Average electric bill: $151.25 a month
Georgia combines below-average housing costs with one of the lower tax burdens in the country and household incomes that sit closer to the national median than most states on this list. Its weak spots are utilities (98.0 on the index, with average bills above the national figure) and health care, which prices at about the national average.
Georgia is also a clear case of a state average being pulled by one metro. The Atlanta region is where most of the state’s population and most of its higher-priced housing are concentrated, while smaller cities and rural areas are considerably cheaper. Georgia has been gradually lowering its flat income tax rate in recent years, so check the Georgia Department of Revenue for the rate that applies to the year you move.
12. Nebraska
- Cost of living index: 90.1 (tied with Georgia)
- Main cities: Omaha, Lincoln, Bellevue, Grand Island, and Kearney
- Best fit: renters and households that want low utility and transportation costs
- Utilities component: 89.4
- Health care component: 104.4
- Median household income: $76,475
- State-local tax burden: 11.5 percent, 38th lowest (calendar year 2022)
- Average electric bill: $110.28 a month, among the lowest in the country
Nebraska has some of the cheapest electricity in the country and a low transportation component (85.6), alongside solid household incomes. On prices alone, it is a strong option.
Taxes are the reason to look twice. Nebraska ranked 38th of 50 on the Tax Foundation’s 2022 burden study, the highest burden of any state in the top 15. Property taxes are a large part of that picture. Nebraska has been cutting its top income tax rate in stages since then, but a homeowner should still price the property tax on a specific address before treating the state’s index score as the full story.
13. New Mexico
- Cost of living index: 90.2
- Main cities: Albuquerque, Las Cruces, Rio Rancho, Santa Fe, and Roswell
- Best fit: people who want a lower-cost option in the West and some of the lowest utility bills in the country
- Utilities component: 79.4
- Housing component: 82.4, the highest in the top 15
- Median household income: $64,059
- State-local tax burden: 10.2 percent, 25th lowest
- Average electric bill: $92.88 a month, among the lowest in the country
New Mexico is the least expensive state in the West on the C2ER index and the only Western state in the top 15. It gets there on utilities and day-to-day costs rather than housing, which is pricier than in any other state ranked above it. Its average electric bill is among the lowest in the country, and the EIA notes that the states with the lowest residential bills are concentrated in the Rocky Mountain region, where both prices and consumption tend to be low.
Incomes are comparatively low, so New Mexico suits households bringing income from elsewhere better than those relying on the local job market.
14. North Dakota
- Cost of living index: 90.5
- Main cities: Fargo, Bismarck, Grand Forks, Minot, and West Fargo
- Best fit: working households that want a low tax burden and incomes near the national median
- Health care component: 106.7, the highest in the top 15
- Utilities component: 82.9
- Median household income: $76,657
- State-local tax burden: 8.8 percent, 7th lowest
- Average electric bill: $118.38 a month
North Dakota pairs a low tax burden, low utility costs, and incomes near the national median, a combination that makes it more affordable for a working household than its 14th-place price rank suggests. Fargo is its largest city, followed by Bismarck, the state capital.
Its weakness is health care, priced well above average. And the BEA’s 2024 data contains a useful warning about using any single year: North Dakota had the largest decline in real personal income of any state that year, at 2.2 percent, because its prices rose 3.5 percent while its residents’ income rose only 1.2 percent. Energy-producing states can see prices and incomes move quickly with commodity cycles.
15. Texas
- Cost of living index: 90.8
- Main cities: Houston, San Antonio, Dallas, Austin, Fort Worth, El Paso, and dozens of fast-growing suburbs
- Best fit: renters, high earners who benefit from no state income tax, and households willing to live outside the largest metros
- BEA price parity (2024): 97.1
- Utilities component: 100.6, the only state in the top 15 above the national average
- Median household income: $78,476
- State-local tax burden: 8.6 percent, 6th lowest
- Average electric bill: $163.72 a month
How affordable Texas is depends heavily on where you live. Its participating cities average 90.8 on the C2ER index, 15th in the country. The federal measure, which weights the whole state by where people live and what they buy, puts it at 97.1, only about 3 percent below the national price level, because so many Texans live in its larger, pricier metros: the BEA’s 2024 price parity for Dallas-Fort Worth-Arlington was 103.1, above the national average, and Austin-Round Rock was 98.1. Most Texans live in large metros, so the statewide federal figure reflects them heavily.
Texas has no personal income tax, and its overall tax burden ranked sixth lowest in 2022. But it funds much of local government through property taxes, so the tax advantage is largest for renters and high earners and smaller for homeowners in high-rate taxing districts. Electricity is another catch: the average Texas bill of $163.72 a month is the sixth highest in the country and above California’s. Adjusted for state prices, Texas’s median household income is roughly $80,800, essentially equal to the U.S. median. Among the states that can be checked this way, only Iowa comes out ahead.
Just Outside the Top 15: Louisiana, Michigan, South Carolina, Ohio, and South Dakota
These five states sit just below the top 15 on the second-quarter 2026 index. All are below the national average, and for some households, one of them will be a better fit than a state ranked above it, because a point or two on the index matters less than the specific costs each one carries.
16. Louisiana
Index 91.3. Louisiana has low housing (81.3) and utility (85.8) components, but two costs outside the index weigh on it heavily. Its households used more electricity on average than any other state’s in 2024, according to the EIA, and quote-based estimates consistently place it among the most expensive states in the country for homeowners insurance, with some putting it first relative to household income. Renters are far less exposed to the insurance problem than buyers.
17. Michigan
Index 92.1. Michigan pairs moderate prices with one of the lowest tax burdens in the country (8.6 percent, fifth lowest in 2022), a low health care component (86.9), and an average electric bill well below the national figure ($119.31). It rarely makes top-ten lists because its housing component (82.9) is higher than in the cheapest Southern states, but on a combined basis of prices and taxes it competes with several states ranked above it.
18. South Carolina
Index 92.7. South Carolina has the 9th-lowest tax burden in the Tax Foundation’s 2022 study and a below-average housing component (79.5). Its grocery, transportation, and health care components all sit within three points of the national average, and its average electric bill ($149.51) runs above it. Coastal areas carry the additional consideration of wind and flood exposure when you price insurance.
19. Ohio
Index 93.0. Ohio’s housing component (85.8) is higher than in most states above it, but it is close to average or below on almost everything else, and its electric bills ($135.16) are below the national figure. Its tax burden ranked 24th in 2022. Ohio is a middle-of-the-pack state on most measures, which is often a strength rather than a weakness for a household that wants few surprises.
21. South Dakota
Index 93.5. South Dakota ranks 21st on the C2ER index, held back by a high health care component (107.4) and a housing component (86.3) above most of its neighbors. Sioux Falls and Rapid City are its largest cities. It has no personal income tax and the fourth-lowest state-local tax burden in the Tax Foundation’s 2022 study, so like Tennessee, it is likely more affordable for a working household than its index rank suggests.
The Most Affordable States by Region
If you already know which part of the country you want to live in, the regional picture is more useful than the national ranking. Of the 15 cheapest states, eight are in the South, six are in the Midwest, one is in the West, and none are in the Northeast. Regions below follow the Census Bureau’s definitions, with scores from the MERIC table for the second quarter of 2026.
The South
The South has the single cheapest state and the deepest bench of affordable options. Thirteen of its 16 states score below the national average.
- Cheapest: Oklahoma (83.0), Alabama (86.0), West Virginia (87.0), Mississippi (87.4), and Arkansas (89.0)
- Also below average: Tennessee (89.7), Georgia (90.1), Texas (90.8), Louisiana (91.3), South Carolina (92.7), Kentucky (94.0), North Carolina (96.7), and Virginia (99.0)
- Above average: Delaware (100.6), Florida (100.8), and Maryland (118.8), plus the District of Columbia (133.8)
The trade-offs that come up most often in the South are high summer electric bills and, in Gulf and Plains states, high homeowners insurance. Both are covered in their own sections below.
The Midwest
The Midwest is the most consistently affordable region in the country. Every one of its 12 states scores below the national average.
- Cheapest: Iowa (86.1), Kansas (87.1), Missouri (88.2), Indiana (89.7), and Nebraska (90.1)
- Also below average: North Dakota (90.5), Michigan (92.1), Ohio (93.0), Minnesota (93.4), South Dakota (93.5), Illinois (94.5), and Wisconsin (95.7)
Midwestern states tend to pair low prices with incomes closer to the national median than the cheapest Southern states, which makes the region a strong fit for households that will earn a local wage. Several have higher tax burdens than their Southern counterparts, and winter heating costs are a real line item.
The West
Affordable options are scarcer in the West, where housing costs run high in most states. Four Western states score below the national average.
- Below average: New Mexico (90.2), Wyoming (94.4), Utah (98.4), and Idaho (99.4)
- Above average: Colorado (102.7), Nevada (105.4), Montana (106.0), Arizona (108.6), Oregon (110.4), Washington (115.1), Alaska (124.5), California (140.3), and Hawaii (185.8)
New Mexico is the clear value in the region, helped by some of the lowest electric bills in the country. Wyoming adds the advantage of no personal income tax and one of the lowest state-local tax burdens in the country.
The Northeast
The Northeast is the most expensive region overall. Only Pennsylvania scores below the national average, at 95.3. Every other Northeastern state is above it: Connecticut (103.6), New Hampshire (108.5), Rhode Island (110.9), Maine (112.9), Vermont (113.4), New Jersey (119.2), New York (132.6), and Massachusetts (148.1). For households committed to the region, Pennsylvania’s smaller cities and towns are generally the most affordable options.
All 50 States Ranked by Cost of Living Index
Here is the full MERIC table for the second quarter of 2026, from cheapest to most expensive. It includes the District of Columbia and Puerto Rico, which MERIC lists alongside the states, so the ranks run to 52. Each entry shows the composite score followed by the six components that make it up. The section after the regional and most-expensive lists explains how the index is built.
- Oklahoma: composite 83.0 (groceries 94.1, housing 65.1, utilities 97.6, transportation 83.9, health care 96.7, miscellaneous 87.8)
- Alabama: composite 86.0 (groceries 95.2, housing 68.6, utilities 94.1, transportation 90.9, health care 85.2, miscellaneous 93.8)
- Iowa: composite 86.1 (groceries 96.2, housing 70.6, utilities 81.7, transportation 93.5, health care 93.0, miscellaneous 93.4)
- West Virginia: composite 87.0 (groceries 96.4, housing 69.9, utilities 93.3, transportation 97.7, health care 88.6, miscellaneous 93.4)
- Kansas: composite 87.1 (groceries 95.3, housing 78.7, utilities 96.0, transportation 84.4, health care 89.4, miscellaneous 88.9)
- Mississippi: composite 87.4 (groceries 94.2, housing 70.8, utilities 97.4, transportation 92.3, health care 84.8, miscellaneous 95.6)
- Missouri: composite 88.2 (groceries 95.3, housing 77.7, utilities 94.0, transportation 85.3, health care 95.4, miscellaneous 92.6)
- Arkansas: composite 89.0 (groceries 94.6, housing 76.9, utilities 98.7, transportation 91.5, health care 85.5, miscellaneous 94.6)
- Indiana: composite 89.7 (groceries 98.2, housing 77.5, utilities 92.7, transportation 98.1, health care 89.7, miscellaneous 93.7)
- Tennessee: composite 89.7 (groceries 96.3, housing 80.0, utilities 88.0, transportation 93.0, health care 89.5, miscellaneous 95.0)
- Georgia: composite 90.1 (groceries 97.2, housing 77.6, utilities 98.0, transportation 90.7, health care 100.2, miscellaneous 94.1)
- Nebraska: composite 90.1 (groceries 98.8, housing 76.5, utilities 89.4, transportation 85.6, health care 104.4, miscellaneous 97.6)
- New Mexico: composite 90.2 (groceries 95.8, housing 82.4, utilities 79.4, transportation 92.7, health care 100.3, miscellaneous 95.2)
- North Dakota: composite 90.5 (groceries 95.5, housing 77.0, utilities 82.9, transportation 91.5, health care 106.7, miscellaneous 99.4)
- Texas: composite 90.8 (groceries 96.0, housing 77.2, utilities 100.6, transportation 95.9, health care 97.6, miscellaneous 95.7)
- Louisiana: composite 91.3 (groceries 95.2, housing 81.3, utilities 85.8, transportation 95.3, health care 95.4, miscellaneous 98.2)
- Michigan: composite 92.1 (groceries 99.1, housing 82.9, utilities 98.1, transportation 97.7, health care 86.9, miscellaneous 94.8)
- South Carolina: composite 92.7 (groceries 99.1, housing 79.5, utilities 95.4, transportation 97.3, health care 99.0, miscellaneous 98.6)
- Ohio: composite 93.0 (groceries 98.6, housing 85.8, utilities 96.3, transportation 92.7, health care 96.7, miscellaneous 95.4)
- Minnesota: composite 93.4 (groceries 99.2, housing 79.1, utilities 95.4, transportation 93.0, health care 114.4, miscellaneous 100.0)
- South Dakota: composite 93.5 (groceries 98.4, housing 86.3, utilities 84.5, transportation 94.4, health care 107.4, miscellaneous 97.5)
- Kentucky: composite 94.0 (groceries 102.0, housing 79.4, utilities 87.0, transportation 98.4, health care 94.8, miscellaneous 103.8)
- Wyoming: composite 94.4 (groceries 99.6, housing 88.5, utilities 88.0, transportation 89.5, health care 97.7, miscellaneous 99.6)
- Illinois: composite 94.5 (groceries 98.9, housing 83.3, utilities 99.9, transportation 100.8, health care 104.2, miscellaneous 98.1)
- Pennsylvania: composite 95.3 (groceries 98.7, housing 84.8, utilities 109.5, transportation 99.4, health care 97.6, miscellaneous 98.2)
- Wisconsin: composite 95.7 (groceries 99.2, housing 91.2, utilities 96.6, transportation 96.1, health care 102.9, miscellaneous 96.8)
- North Carolina: composite 96.7 (groceries 101.0, housing 91.4, utilities 96.2, transportation 94.2, health care 107.9, miscellaneous 98.8)
- Utah: composite 98.4 (groceries 98.5, housing 102.9, utilities 81.5, transportation 104.4, health care 90.4, miscellaneous 98.3)
- Virginia: composite 99.0 (groceries 100.4, housing 99.3, utilities 98.8, transportation 99.6, health care 95.6, miscellaneous 98.4)
- Idaho: composite 99.4 (groceries 103.8, housing 98.4, utilities 73.9, transportation 105.6, health care 99.7, miscellaneous 103.2)
- Delaware: composite 100.6 (groceries 101.6, housing 99.1, utilities 99.7, transportation 96.8, health care 103.0, miscellaneous 102.3)
- Florida: composite 100.8 (groceries 104.9, housing 99.3, utilities 97.5, transportation 103.3, health care 102.8, miscellaneous 100.1)
- Puerto Rico: composite 101.1 (groceries 107.8, housing 96.5, utilities 164.1, transportation 94.3, health care 68.7, miscellaneous 92.6)
- Colorado: composite 102.7 (groceries 101.1, housing 108.6, utilities 85.4, transportation 97.5, health care 101.8, miscellaneous 104.2)
- Connecticut: composite 103.6 (groceries 103.0, housing 97.0, utilities 124.3, transportation 99.3, health care 105.3, miscellaneous 105.4)
- Nevada: composite 105.4 (groceries 103.2, housing 119.0, utilities 75.8, transportation 117.0, health care 105.4, miscellaneous 98.7)
- Montana: composite 106.0 (groceries 103.8, housing 114.9, utilities 80.7, transportation 101.4, health care 103.9, miscellaneous 106.9)
- New Hampshire: composite 108.5 (groceries 99.8, housing 113.9, utilities 115.9, transportation 100.4, health care 103.7, miscellaneous 108.4)
- Arizona: composite 108.6 (groceries 99.6, housing 120.5, utilities 102.4, transportation 107.1, health care 98.0, miscellaneous 105.5)
- Oregon: composite 110.4 (groceries 103.7, housing 118.8, utilities 97.7, transportation 118.6, health care 115.4, miscellaneous 106.3)
- Rhode Island: composite 110.9 (groceries 103.4, housing 117.1, utilities 123.1, transportation 97.4, health care 103.0, miscellaneous 110.2)
- Maine: composite 112.9 (groceries 101.1, housing 128.5, utilities 128.3, transportation 96.9, health care 115.8, miscellaneous 104.3)
- Vermont: composite 113.4 (groceries 100.1, housing 128.2, utilities 113.7, transportation 100.2, health care 109.0, miscellaneous 110.4)
- Washington: composite 115.1 (groceries 105.4, housing 124.6, utilities 100.6, transportation 128.7, health care 111.3, miscellaneous 111.8)
- Maryland: composite 118.8 (groceries 108.2, housing 144.1, utilities 116.1, transportation 105.2, health care 105.2, miscellaneous 107.4)
- New Jersey: composite 119.2 (groceries 107.6, housing 145.1, utilities 108.7, transportation 103.6, health care 116.1, miscellaneous 108.8)
- Alaska: composite 124.5 (groceries 125.1, housing 126.7, utilities 148.9, transportation 98.6, health care 130.6, miscellaneous 122.1)
- New York: composite 132.6 (groceries 102.5, housing 194.8, utilities 108.7, transportation 104.6, health care 108.9, miscellaneous 108.0)
- District of Columbia: composite 133.8 (groceries 108.0, housing 186.9, utilities 110.3, transportation 107.6, health care 119.7, miscellaneous 113.3)
- California: composite 140.3 (groceries 110.0, housing 192.1, utilities 131.5, transportation 137.1, health care 110.4, miscellaneous 115.6)
- Massachusetts: composite 148.1 (groceries 105.3, housing 213.2, utilities 159.8, transportation 106.8, health care 129.7, miscellaneous 120.2)
- Hawaii: composite 185.8 (groceries 135.8, housing 302.6, utilities 207.3, transportation 136.9, health care 103.0, miscellaneous 124.5)
A few patterns stand out once you read the components rather than the composite:
- Groceries barely move. Grocery components for the 15 cheapest states fall between 94.1 and 98.8. Outside Alaska and Hawaii, food is close to a national price, so it rarely decides where you can afford to live.
- Housing does almost all the work. Housing components in the top 15 run from 65.1 to 82.4. Among the five most expensive places, they run from 186.9 in the District of Columbia to 302.6 in Hawaii. When people say a state is cheap, they almost always mean its housing is cheap.
- Utilities scramble the order. Several Western states have unusually low utility components (Idaho 73.9, Nevada 75.8, New Mexico 79.4), while some cheap Southern states sit near or above average. The section on electric bills explains why the utilities component can understate what Southern households actually pay.
- Health care runs opposite to the stereotype. Mississippi (84.8), Alabama (85.2), and Arkansas (85.5) have the lowest health care components on the list, while North Dakota (106.7), South Dakota (107.4), and Minnesota (114.4) run well above average. These are prices for a standard set of services, not measures of access or quality.
The Most Expensive States, for Context
If you are deciding whether to leave a high-cost state, it helps to see where the top of the scale sits. On the MERIC table for the second quarter of 2026, the most expensive places were:
- Hawaii: 185.8, with a housing component of 302.6
- Massachusetts: 148.1
- California: 140.3
- District of Columbia: 133.8
- New York: 132.6
On the BEA’s 2024 measure, which covers all consumers statewide, the highest price levels were California (110.7), Hawaii (110.0), and New Jersey (108.8), with the District of Columbia at 109.9. The Tax Foundation’s 2022 study found the highest state-local tax burdens in New York (15.9 percent of income), Connecticut (15.4 percent), and Hawaii (14.1 percent).
Two things are worth noticing. First, the gap between the most and least expensive states is much smaller on the federal measure (about 24 points between California and Arkansas) than on the C2ER index (about 103 points between Hawaii and Oklahoma). If you earn an average income and live an average lifestyle, the federal gap is probably closer to what you would actually experience. Second, high-cost states tend to have high incomes, which is why the BEA finds a positive relationship between price levels and income across states. Moving from an expensive state to a cheap one is most clearly worthwhile when your income comes with you.
How These States Were Ranked
The ranking in this guide comes from the C2ER Cost of Living Index, using the state-level table MERIC published for the second quarter of 2026. C2ER has published the index since 1968, and it is one of the most widely used sources for comparing living costs between places. A score of 100 is the national average.
A few things about the index are worth knowing when you use it to choose a state:
- It prices a specific household. C2ER measures costs for professional and managerial households in the top fifth of incomes, at the stores and in the kinds of housing that household typically uses.
- It covers cities, not whole states. Prices are collected each quarter in participating urban areas, and MERIC averages a state’s participating cities to produce its score. Small towns and rural areas, which are often cheaper still, are largely outside the measure.
- It leaves out taxes. C2ER states that the index excludes taxes, so this guide covers them separately.
- Small differences are not meaningful. C2ER cautions against reading too much into small gaps between scores, and a state’s rank can shift a few places from one quarter to the next as the set of surveyed cities changes. Treat states within a point or two of each other as roughly equal.
To check the C2ER results, this guide also uses the Bureau of Economic Analysis’s regional price parities, the federal government’s measure of price levels by state. The BEA’s figures cover every consumer in a state, rural and urban, and are weighted by what residents actually buy. Its 2024 data, released in February 2026, put Arkansas, Mississippi, Iowa, and Oklahoma at the lowest price levels in the country, the same states that lead the C2ER list. The BEA’s next release, covering 2025, is scheduled for December 10, 2026, and MERIC updates its state table each quarter.
Incomes come from the Census Bureau’s 2020–2024 American Community Survey, tax burdens from the Tax Foundation’s most recent state-local tax burden study (calendar year 2022), and electric bills from the EIA’s 2024 residential data.
Taxes in the Most Affordable States
Taxes are not part of the cost of living index, so they deserve their own look. For many households, what you owe to the state, county, city, and school district is the second-largest cost difference between states after housing.
Where the cheapest states land on tax burden
The best available comparison is the Tax Foundation’s state-local tax burden study, which estimates all state and local taxes paid by a state’s residents as a share of that state’s income. Its most recent edition covers calendar year 2022. Ranked from lowest burden (1) to highest (50), the 15 cheapest states on the C2ER index fall like this:
- Low burden (top 10): Tennessee (3rd, 7.6 percent), Texas (6th, 8.6 percent), North Dakota (7th, 8.8 percent), Georgia (8th, 8.9 percent), Oklahoma (10th, 9.0 percent)
- Middle (11th to 30th): Missouri (13th, 9.3 percent), Indiana (14th, 9.3 percent), Alabama (20th, 9.8 percent), Mississippi (21st, 9.8 percent), West Virginia (22nd, 9.8 percent), New Mexico (25th, 10.2 percent), Arkansas (26th, 10.2 percent)
- Higher burden (31st to 50th): Kansas (33rd, 11.2 percent), Iowa (34th, 11.2 percent), Nebraska (38th, 11.5 percent)
For comparison, the study’s U.S. average was 11.2 percent, the median state was at 10.2 percent, and the highest burdens were in New York (15.9 percent), Connecticut (15.4 percent), and Hawaii (14.1 percent). Kansas and Iowa sit right at the U.S. average and Nebraska slightly above it, while every other state in the top 15 is below it. The spread between Tennessee and Nebraska is nearly four percentage points of statewide income, a meaningful gap even before you account for your own circumstances.
Why these figures need care
- They describe the whole state, not your household. The Tax Foundation measures total taxes paid by all residents relative to total state income. Your own bill depends on whether you rent or own, what you earn, what you buy, and where exactly you live.
- They are not current. State tax law has changed a great deal since 2022. The Tax Foundation reports that 26 states have enacted individual income tax rate reductions since 2021, including several on this list. Iowa, Mississippi, Georgia, Arkansas, Nebraska, and Oklahoma have all cut or restructured income taxes in the years since the study’s data year.
- Small differences can mean large shifts in rank. The Tax Foundation notes that state burdens cluster closely, so a change of a fraction of a percentage point can move a state many places.
- No income tax does not mean low taxes. States without a wage income tax collect revenue in other ways. Tennessee relies heavily on sales taxes. Texas relies heavily on property taxes. Whether that works in your favor depends on your mix of income, spending, and property.
What to do with this
Treat the burden study as a first filter, not an answer. Before you commit to a state, look up the current income tax rules on its department of revenue website, the property tax rate for the specific county and city you are considering (usually published by the county assessor or tax collector), and the combined sales tax rate where you would shop. If you have retirement income, check separately how the state treats Social Security, pensions, and retirement account withdrawals, since those rules vary widely and change often.
This section is general information, not tax advice. Tax law changes frequently, and how it applies to you depends on details a qualified tax professional can evaluate.
Homeowners Insurance in the Most Affordable States
Homeowners insurance has become one of the fastest-rising costs of owning a home, and it varies enormously by location. It is also one of the costs most likely to undo the savings of a move to a cheap state, because several of the states with the lowest housing prices sit in regions with high exposure to severe storms, hurricanes, or hail.
What the federal data shows
In January 2025, the U.S. Treasury’s Federal Insurance Office released what it described as the most comprehensive data on homeowners insurance ever assembled, built with state insurance regulators and covering more than 246 million policies from 330 insurers between 2018 and 2022. Among its findings:
- Premiums rose faster than inflation. Average homeowners premiums increased 8.7 percent faster than the rate of inflation over the period.
- Risk drives cost. Homeowners in the 20 percent of ZIP codes with the highest expected annual losses from climate-related perils paid an average of $2,321 in premiums, 82 percent more than those in the lowest-risk 20 percent of ZIP codes.
- Availability tightens with risk. Nonrenewal rates in the highest-risk ZIP codes were about 80 percent higher than in the lowest-risk ones.
The key word is ZIP code. Insurance cost is set at the level of the property, not the state, and it can differ substantially between two towns in the same county.
Why state-level premium figures conflict
You will find widely different “average premium by state” figures online, and the differences are not small. One widely cited estimate for 2023 put Florida’s average annual premium near $11,000, while another estimate for early 2023 put it under $6,000. Both can be honest, because they measure different things. Quote-based estimates price a standard policy at a set coverage amount, often a $300,000 dwelling. Regulator data reflects premiums actually paid on existing policies, which lags by several years and reflects whatever coverage people bought.
Where these sources agree is on which states are expensive. Quote-based estimates repeatedly place Louisiana, Oklahoma, Texas, and Florida among the most expensive states for homeowners insurance, with Mississippi and Alabama often not far behind. Oklahoma, Texas, Mississippi, and Alabama are all in the top 15 on the cost of living index, and Louisiana ranks 16th.
What to do with this
- Get real quotes on a real address before you make an offer on a home, not after. Ask for the premium, the deductible structure (many storm-prone areas use a separate, percentage-based deductible for wind or hail), and what is excluded.
- Check flood separately. Standard homeowners policies generally do not cover flood damage. Ask whether the property is in a mapped flood zone and what flood coverage would cost.
- Renters are far less exposed. Renters insurance covers belongings and liability, not the building, so it is much less sensitive to these regional swings. If you are renting first in a new state, the insurance problem mostly belongs to your landlord, though it can still show up in rent over time.
- Ask your state insurance department. Most publish consumer guides and complaint data, and some publish average premium comparisons.
Insurance is the cost most likely to surprise a household moving from a low-risk region to a cheap state in a high-risk one. A home that costs a third less than where you live now can carry an insurance bill that is several times higher.
Electric Bills in the Most Affordable States
Utility costs vary more among the cheapest states than almost any other expense, and the cost of living index understates the gap because it prices energy for a standardized home. What you actually pay is price multiplied by how much you use, and use varies enormously by climate and by how homes are heated and cooled.
Price and bill are not the same thing
The EIA’s 2024 data on average monthly residential electric bills makes the point sharply. The national average bill was $142.26, on average use of 863 kilowatt-hours a month at 16.48 cents per kilowatt-hour. Here is how the cheapest states compare:
- Above the national average bill: Alabama ($173.50), Texas ($163.72), Mississippi ($154.83), West Virginia ($154.76), Georgia ($151.25), and Tennessee ($143.32)
- Below the national average bill: Indiana ($133.06), Oklahoma ($132.05), Missouri ($129.18), Arkansas ($129.13), Kansas ($123.90), North Dakota ($118.38), Iowa ($111.54), Nebraska ($110.28), and New Mexico ($92.88)
Several of the cheapest states have lower electricity prices per kilowatt-hour than the national average and still have higher bills, because households there use far more electricity. Alabama households used an average of 1,143 kilowatt-hours a month in 2024 and Mississippi households 1,156, compared with 503 in California. California’s price per kilowatt-hour was roughly double Alabama’s, yet the average Alabama bill was higher.
What drives the difference
- Cooling. Long, hot summers in the Deep South and Texas mean many months of heavy air conditioning use.
- Heating fuel. Many Southern homes heat with electricity, while many Northern and Midwestern homes heat with natural gas or propane. That makes Southern electric bills look high and Northern electric bills look low, even though Northern households may have a separate, substantial gas bill in winter. The EIA figures above cover electricity only.
- Home size and age. Larger and older homes typically use more energy. In a low-cost state, the same budget often buys a bigger house, which can raise the utility bill even as the mortgage falls.
What to do with this
Ask for 12 months of utility history on any home or apartment you are seriously considering. Many utilities will provide an address’s average monthly bill on request, and sellers and landlords can usually share past bills. A full year matters, because a home that is cheap to run in April can be expensive in August or January. If the home uses gas or propane, ask for those bills too.
Health Care and Transportation Costs in the Most Affordable States
Housing decides which states are cheap. Health care and transportation decide the order among them, and they are the two components where your own situation matters most.
Health care
The C2ER health care component prices a standard set of services, such as an office visit with a doctor, a dental visit, and common prescriptions. On that measure, several of the cheapest states are also the cheapest for care:
- Lowest in the country: Mississippi (84.8), Alabama (85.2), and Arkansas (85.5)
- Above the national average within the top 15: North Dakota (106.7), Nebraska (104.4), New Mexico (100.3), and Georgia (100.2)
Two things the component does not measure are access and insurance premiums. A low price for an office visit does not help if the nearest specialist is two hours away, and many of the lowest-cost areas in these states are rural. If you or someone in your household needs regular specialist care, check the distance to the hospitals and practices you would actually use, and check which insurance plans are available in the county you are considering before you treat the health care component as a saving.
If you are retiring, this matters even more. Our state-by-state retirement guides, including the best cities to retire in Tennessee and the best cities to retire in Texas, compare specific cities on hospital access alongside taxes and insurance.
Transportation
The transportation component prices things like gasoline, auto maintenance, and, where relevant, public transit fares. The cheapest states for it are the Plains and lower Midwest:
- Lowest in the country: Oklahoma (83.9), Kansas (84.4), Missouri (85.3), and Nebraska (85.6)
- Near the national average within the top 15: Indiana (98.1), West Virginia (97.7), and Texas (95.9)
What the component does not capture is how much you drive. Most of the cheapest states are car-dependent outside their largest cities, and many households need two vehicles where they might have needed one, or none, in a dense city. A household moving from a city where it relied on transit should budget for buying, insuring, and maintaining a car, which can offset a meaningful share of the housing savings in the first few years.
Incomes in the Most Affordable States
A low price level helps only if your income does not fall by more than your costs do. This is the single most important question for anyone moving to a cheaper state, and price indexes cannot answer it, because they do not look at income at all.
How to adjust income for local prices
The BEA’s regional price parities let you convert an income in one state into its purchasing power at national-average prices. Divide the income by the state’s price parity, then multiply by 100. Using each state’s 2024 price parity and its median household income from the Census Bureau’s 2020–2024 American Community Survey (reported in 2024 dollars):
- Iowa: $75,059 ÷ 0.878 ≈ $85,500, about 6 percent above the U.S. median
- Texas: $78,476 ÷ 0.971 ≈ $80,800, about equal to the U.S. median
- Missouri: $70,702 ÷ 0.908 ≈ $77,900, about 4 percent below
- Tennessee: $69,595 ÷ 0.919 ≈ $75,700, about 6 percent below
- Oklahoma: $65,039 ÷ 0.878 ≈ $74,100, about 8 percent below
- Arkansas: $60,773 ÷ 0.869 ≈ $69,900, about 13 percent below
- Mississippi: $56,447 ÷ 0.870 ≈ $64,900, about 20 percent below
The U.S. median household income in the same Census series was about $80,700. The pattern is consistent: in most of the cheapest states, low prices offset some of the lower incomes but not all of it. Local residents, on average, are not better off in real terms than the national median. The exceptions on this list are Iowa and, roughly, Texas.
What this means for different movers
- If your income is portable (remote work at the same salary, a pension, Social Security, investment income), you keep your income and get the lower prices. This is the case where a cheap state delivers the full benefit, and the price indexes are the right guide.
- If you will take a local job, compare offers in your own field, not state medians. Pay gaps between states vary by occupation, and some professions pay close to national rates everywhere while others track local wage levels closely.
- If your employer adjusts pay by location, ask how. Some remote employers reduce salaries for lower-cost areas, which can erase much of the gain.
One simple test: take the salary you would earn in the new state, divide by its price parity as above, and compare it with your current salary divided by your current state’s price parity. If the new number is not clearly higher, the move is not a financial improvement on prices alone, though it may still be worth making for other reasons.
The Cheapest Places Within the Most Affordable States
Choosing a state is only half the decision. Within any state, the largest metro area is usually the most expensive place to live and smaller cities, towns, and rural counties are the least expensive, and the gap is often larger than the gap between neighboring states. Texas and Missouri show how much it can matter.
Texas: one state, a 19-point spread
The BEA’s 2024 price parities show how wide the range can be inside a single state. Texas as a whole came in at 97.1. Its metro areas ranged from 103.1 in Dallas-Fort Worth-Arlington, above the national average, to 84.0 in the Texarkana metro area, which spans the Texas-Arkansas line. Austin-Round Rock sat at 98.1, El Paso at 89.9, and Amarillo at 91.8. A household moving to Dallas-Fort Worth is moving to a place that costs more than the national average, even though Texas regularly appears on lists of the cheapest states.
Missouri: metro versus rural
The BEA also splits states into their metro and nonmetro portions. In 2024, Missouri’s metro counties had a price level of 92.6 and its nonmetro counties 83.9, a difference of nearly nine points within the same state. On the C2ER side, Missouri’s participating cities ranged from 83.8 in Joplin to 91.6 in Springfield in the second quarter of 2026.
What to do with this
Decide on a metro area or region before you lean on any state-level number. Then look for that area specifically: C2ER and MERIC publish city figures for participating areas, and the BEA publishes price parities for metropolitan areas. If you are open to living outside a metro, look at small cities and towns within commuting or driving distance of the services you need, since that is where the largest savings usually are. For ideas, our guide to the best small cities to live in compares 15 smaller places on cost and the trade-offs that come with them.
What It Costs to Move to a Cheaper State
Every list of cheap states assumes you are already there. Getting there costs money, and on an interstate move it can cost a lot. The savings from a lower cost of living only start once you have paid that bill, so it belongs in the math.
The costs to budget for
- The move itself. Professional interstate moves are usually priced by the weight of the shipment and the distance, plus packing, valuation coverage, and extra services. Do-it-yourself options (rental trucks, portable containers, freight trailers) cost less in cash and more in time and effort.
- Overlap housing costs. Many movers pay rent or a mortgage in two places for a month or more, or pay for temporary housing while they look for a permanent home.
- Selling and buying. If you own, selling one home and buying another involves commissions, closing costs, and often repairs or staging. These can dwarf the cost of the truck.
- Deposits and setup. Security deposits, utility deposits and connection fees, and new furniture or appliances for a different-sized home.
- Vehicle and license changes. New registration, title transfer, and driver’s license fees, plus any change in auto insurance premiums, which also vary by state and ZIP code.
- Travel. Getting your household, pets, and vehicles to the new state, and any house-hunting trips beforehand.
Our moving cost calculator can help you rough out the move itself, and our guide to how much it costs to move covers the main price drivers in more detail.
Federal rules that protect the price on an interstate move
Interstate moves are regulated by the Federal Motor Carrier Safety Administration, and its rules give you real protection on the biggest line item:
- Written estimates are required. A mover’s quick “rate quote” is not an estimate. The FMCSA advises that an estimate should be based on an actual or virtual inspection of your belongings.
- A binding estimate guarantees you will not pay more than the estimated amount at delivery for the items and services listed. If you add items or services, the mover must prepare a new estimate.
- A non-binding estimate is not a guarantee, but the mover cannot require you to pay more than 110 percent of it at delivery. Any remaining balance is billed later.
- Your Rights and Responsibilities When You Move, the FMCSA booklet, must be provided by interstate movers and explains these rules in plain language.
Those federal rules apply to moves that cross a state line. If your move stays within one state, your state’s rules apply instead, and they vary. Our guide to local vs. long-distance moves explains the difference and how to check a mover’s license in any state.
Ship less, save more
Because interstate moves are usually priced by weight, the cheapest pound to move is the one you leave behind. Before you collect estimates, decide what to sell, donate, or replace at your destination. Bulky, low-value furniture is often cheaper to replace than to ship across the country, especially if you are moving to a state where you will be buying a different-sized home anyway.
A Worked Example: When a Move Pays for Itself
Here is how to put the pieces together. Every number below is hypothetical and chosen to make the arithmetic easy to follow. Substitute your own figures; the method is what matters.
The setup
- Household: two adults, renting, with $90,000 a year in combined income
- Annual spending on goods and services covered by a price index: $55,000 (housing, groceries, utilities, transportation, health care, and everything else, but not taxes or savings)
- Current location price level: 110
- Destination price level: 88
- One-time cost of the move: $12,000, including the move, a month of overlapping rent, deposits, and travel
Step 1: The price saving
The same basket of goods and services costs 88 ÷ 110 = 0.80 as much at the destination, or 20 percent less. Applied to $55,000 of spending, that is a saving of about $11,000 a year, if the household keeps the same lifestyle.
Step 2: Adjust for taxes and insurance
Price indexes leave these out, so add them back. Suppose the household’s state and local taxes are about $1,500 a year lower at the destination, and renters insurance is about the same. The total annual saving rises to about $12,500. If the household were buying a home in a high-insurance region instead, an insurance increase of a few thousand dollars a year could take a large bite out of this figure, which is why Step 2 is not optional.
Step 3: The break-even point
Divide the one-time moving cost by the monthly saving. $12,500 a year is about $1,040 a month, and $12,000 ÷ $1,040 ≈ 11.5 months. After roughly a year, the move has paid for itself, and every month after that is a genuine gain.
Step 4: The income test
Now change one assumption. Instead of keeping $90,000 in income, the household takes local jobs paying 15 percent less, or $76,500. That is $13,500 a year less income, which is more than the $12,500 it saves. On these numbers, the household is worse off every year it stays, and it never recovers the cost of the move.
That is the whole argument of this guide in four steps. A lower price level is a real saving only when your income holds up, and the move itself is a cost you have to earn back. Run the numbers with your own figures before you start collecting moving quotes.
A shortcut formula
Annual gain = (covered spending × (1 − destination index ÷ current index)) + tax savings − added insurance cost − income lost. If the annual gain is positive, divide your one-time moving cost by it to find how many years the move takes to pay back. If it is negative, the move does not pay back on cost alone.
Who Gains the Most From a Low-Cost State
The households that benefit most from a move to a cheaper state share one trait: their income does not depend on local wages. Within that group, a few situations stand out.
- Remote workers who keep their salary. This is the clearest case. If your employer does not adjust pay by location, every point of difference on the price index is close to a direct gain, minus whatever changes in taxes and insurance you face. Confirm your employer’s location pay policy in writing before you move.
- Retirees with pensions, Social Security, and savings. Retirement income moves with you. The considerations that matter most shift toward health care access, how the state taxes retirement income, property tax relief for older homeowners, and distance from family. Our guides to the best cities to retire in South Carolina and North Carolina work through those questions city by city.
- Renters in very high-cost metros. Housing is the component that varies most between states, so households paying the most for housing have the most to gain, especially if they can keep their income.
- People in professions that pay similarly everywhere. Some fields, particularly those with national labor markets or standardized pay scales, pay closer to national rates across states. Workers in those fields lose less income when they move.
- First-time buyers priced out of their current market. In the cheapest states, the housing component sits roughly 18 to 35 percent below the national average. For a household that cannot buy where it lives now, that can be the difference between owning and renting, provided insurance and property taxes on the specific home pencil out.
If you are early in your career, the calculation is different again, because job opportunities and earnings growth often matter more than today’s prices. Our guide to the best cities to live in your 20s weighs rent against what people actually earn in each city.
When Moving to a Cheaper State Does Not Save You Money
Lists of cheap states rarely say this plainly, so we will: for a lot of households, moving to a lower-cost state does not save money, or saves much less than the index difference suggests. These are the most common reasons.
- Your income falls by more than your costs. As the worked example shows, a 15 percent pay cut can wipe out a 20 percent drop in prices, because prices apply only to what you spend while the pay cut applies to everything you earn.
- You move to the expensive part of a cheap state. A cheap state’s largest metro can cost as much as, or more than, the national average. Moving from a moderately priced city to the priciest metro in a “cheap” state can leave your costs roughly unchanged.
- Insurance on the home you buy is far higher. In storm-exposed regions, a homeowners policy can cost several times what it does in a low-risk area. A lower mortgage payment does not help much if the insurance and property tax escrow rise to match it.
- You trade transit for two cars. If you rely on public transit now, the cost of buying, insuring, fueling, and maintaining vehicles can absorb a meaningful share of the housing savings.
- Your utility bills rise. A larger home in a hot climate can carry an electric bill well above what you pay now, even at lower rates.
- You lose a support network you were not paying for. Free child care from family, a spouse’s established career, or a nearby relative who helps with an aging parent all have real dollar values. So do the flights home to visit.
- You plan to move again soon. If you are unlikely to stay long enough to pass the break-even point, the move costs more than it saves.
None of these is a reason not to move. Plenty of people move to a lower-cost state for a better quality of life, to be near family, or for a slower pace, and are glad they did. The point is to make the decision knowing what the numbers actually say rather than what the rankings imply.
How to Check the Numbers for a Specific City
State rankings are a starting point. Before you commit to a move, narrow down to a specific city or county and check these seven things. Most take a few minutes each, and together they will tell you more than any ranking.
- Find the city’s price level, not the state’s. If the city participates in the C2ER survey, its index and component scores give you a direct comparison with where you live now. MERIC publishes Missouri’s participating cities, local economic development organizations often publish their own, and C2ER sells the full city-level dataset. For metro areas, the BEA’s regional price parities are free.
- Price your actual housing. Look at current rental listings or recent sales for the size and type of home you want, in the neighborhoods you would actually consider. Statewide medians are a poor guide to a specific neighborhood.
- Look up the property tax. Your county assessor or tax collector publishes rates. In states that rely heavily on property tax, the rate can vary considerably from one taxing district to the next, even within one city.
- Check the state’s income and sales tax rules on its department of revenue website. Confirm the current rates rather than relying on any list, since many states have changed theirs in recent years. If you have retirement income, check how each type is treated.
- Get insurance quotes for a real address. Homeowners premiums are set by location, construction, and risk. A quote on an actual property is the only reliable number. Ask about flood coverage separately.
- Ask for a year of utility bills. Electric and gas costs depend on the home, the climate, and the heating fuel. Twelve months of history from the seller, landlord, or utility shows the seasonal peaks.
- Compare your income on a price-adjusted basis. Divide the salary you would earn there by the local price level, and compare it with your current salary divided by your current price level. Then run the break-even calculation from the worked example with your actual moving estimate.
Our cost of living calculator is a quick way to compare two cities side by side before you dig into the details above. And if you are still choosing a destination, our guide to the best cities to move to in the US explains what the major city rankings measure and what moving between them costs.
Where 10 Federal Storage Operates Among the Lower-Cost States
The ranking above was built entirely from public data, and it would look the same whether or not we operated in any of these states. Here is where we do, so you can plan the storage side of a move if you need it.
States in the top 15 where we have locations
- Missouri (7th): Columbia and Jefferson City. See our Missouri storage locations.
- Arkansas (8th): seven communities in the Little Rock area, including Little Rock, North Little Rock, Benton, Bryant, Jacksonville, Maumelle, and Sherwood. See our Arkansas storage locations.
- Tennessee (10th): Johnson City, Kingsport, Gray, and Greeneville in northeast Tennessee, and Nolensville south of Nashville. See our Tennessee storage locations.
- Georgia (11th): 20 communities, concentrated on the west and south sides of metro Atlanta, plus Macon, Valdosta, Richmond Hill near Savannah, Dahlonega, and Ringgold. See our Georgia storage locations.
- Texas (15th): more than 50 communities across Dallas-Fort Worth, greater Houston and Galveston County, the Austin and San Antonio areas, Killeen-Temple, and Abilene. See our Texas storage locations.
States just outside the top 15
- Michigan (17th): one location in Washington. See our Michigan storage locations.
- South Carolina (18th): the Spartanburg area (Spartanburg, Boiling Springs, and Inman), the Columbia area (Columbia, West Columbia, and Lexington), and the Grand Strand (Little River and North Myrtle Beach). See our South Carolina storage locations.
Where we do not operate
We have no facilities in Oklahoma, Alabama, Iowa, West Virginia, Kansas, Mississippi, Indiana, Nebraska, New Mexico, North Dakota, Louisiana, Ohio, or South Dakota. If you are moving to one of those states, we cannot help at your destination, and you will want a local provider there. If you are leaving one of the states where we do operate, storage near your current home can still help with staging a sale or bridging the gap before you leave.
We also operate in several states that do not rank among the cheapest, including North Carolina, Illinois, Wisconsin, Virginia, Florida, Colorado, New Hampshire, and Washington. If you are moving out of one of those states toward a lower-cost one, that is often where storage is most useful: at the departure end, while you sell, downsize, or wait for a closing date.
Sizing Storage for a Move to a Lower-Cost State
A move to a cheaper state has a pattern that differs from most moves: households often end up with more space at the destination, not less, because the same budget buys a larger home. That changes when storage helps and how much you need.
Where storage usually helps on this kind of move
- Staging a home for sale in an expensive market. If you are selling in a high-cost area, clearing out extra furniture, décor, and seasonal items helps rooms show better. This is often the single most valuable use of storage on a move to a cheaper state, because the sale price at the departure end is the largest number in the whole move.
- Bridging a gap before closing. If you have to leave your current home before your new one is ready, a unit holds your belongings in between.
- Renting first, buying later. Many people rent in a new state for a few months to learn the area before they buy. A unit near your destination lets you live in a smaller rental with only what you need and keep the rest until you have a permanent address.
- Splitting the move. If you are moving in stages, for example one partner first and the other after a job transition, storage can hold part of the household in the meantime.
How much space
Size the unit by what you are actually storing, not by the number of bedrooms you are leaving. Our storage size calculator lets you add your items and recommends a size, and the storage unit size guide shows what typically fits in each unit. As general starting points:
- Staging extras from a few rooms, or the contents of a studio or one-bedroom: start with small units.
- Part of a two- or three-bedroom home while you rent first or wait for a closing: look at medium units.
- Most or all of a larger home while you search for a permanent address: start with large units.
If you are storing items that are sensitive to temperature swings through a Southern summer or a Plains winter, such as wood furniture, electronics, or photographs, a climate-controlled unit keeps the temperature regulated and protects against extreme heat and cold. Availability varies by facility.
How renting works with us
10 Federal Storage facilities are contactless. You choose and rent a unit online, receive your gate and unit access codes by email and text, and can reach your unit 24/7 at nearly all of our locations. Rentals are month-to-month, a free lock is included with every move-in, and a protection plan is required at checkout. Because there is no staff on site, our facilities cannot accept deliveries or sign for shipments, so plan to be there when your movers or truck arrive.
When You Do Not Need a Storage Unit for This Move
We rent storage units, and we would still rather you not pay for one you do not need. On a move to a lower-cost state, that is more common than on most moves. Skip the unit in these situations:
- You are moving into a bigger home. If your destination home has more space than the one you are leaving, which is common on this kind of move, your belongings may fit with room to spare. Move straight from one home to the other.
- Your dates line up. If you can close or sign a lease at the destination on or before the day you leave, there is no gap to bridge.
- Your gap is short and your mover can hold your goods. On an interstate move, many full-service movers offer storage-in-transit, holding your shipment in their warehouse until you are ready for delivery. For a short, predictable gap, that can be simpler than renting your own unit, because your goods are handled one fewer time and the mover’s liability continues during the storage period. Ask about the maximum storage period and what happens when it ends.
- The items are cheaper to replace than to keep. Multiply a unit’s monthly rent by the number of months you realistically expect to store something. If the total is more than the cost of replacing the items at your destination, sell or donate them before you move. The same logic applies to shipping: bulky, low-value furniture is often cheaper to replace than to move across the country.
- You are storing items with no plan to retrieve them. If you cannot say when or why you would want something back, decide now rather than paying every month to postpone the decision.
- Your destination is a state where we do not operate and you need storage there. A unit with us in the state you are leaving will not help you after you arrive, so look for a provider near your new home.
Storage earns its cost when it solves a timing problem, helps a home sell for more, or protects things you genuinely want to keep while you settle in. If none of those apply, you are better off without it.
Frequently Asked Questions About the Most Affordable States
On the C2ER Cost of Living Index as published by MERIC for the second quarter of 2026, Oklahoma was the cheapest state, with a composite score of 83.0, about 17 percent below the national average. On the Bureau of Economic Analysis’s 2024 regional price parities, Arkansas had the lowest overall price level at 86.9, with Mississippi close behind at 87.0. Both measures put the cheapest states in the South and the Midwest.
On the C2ER index for the second quarter of 2026, the ten cheapest states were Oklahoma, Alabama, Iowa, West Virginia, Kansas, Mississippi, Missouri, Arkansas, Indiana, and Tennessee. Rankings shift from quarter to quarter, and states within a point or two of each other are effectively tied, so the exact order matters less than which states appear on the list consistently.
Oklahoma had the lowest housing component of any state on the C2ER Cost of Living Index for the second quarter of 2026, at 65.1, about 35 percent below the national average. For renters specifically, the Bureau of Economic Analysis found that West Virginia had the lowest housing rents of any state in 2024, at about 46 percent below the national level.
The C2ER Cost of Living Index, the most common basis for state cost of living comparisons, does not. C2ER states that the index excludes taxes and non-consumer expenditures. To compare taxes between states, use a separate source such as the Tax Foundation’s state-local tax burden study, and confirm current rules with each state’s department of revenue.
Oklahoma, which the Census Bureau includes in the South region, ranked cheapest of all states on the C2ER index for the second quarter of 2026, followed by Alabama. On the BEA’s 2024 price parities, Arkansas and Mississippi had the lowest price levels in the country.
Iowa ranked as the cheapest Midwestern state on the C2ER index for the second quarter of 2026, at 86.1, with Kansas close behind at 87.1. Iowa also had one of the lowest overall price levels on the BEA’s 2024 measure, at 87.8.
New Mexico ranked as the least expensive Western state on the C2ER index for the second quarter of 2026, at 90.2, largely because of low utility costs. It was the only Western state among the 15 cheapest.
Pennsylvania ranked as the least expensive Northeastern state on the C2ER index for the second quarter of 2026, at 95.3, slightly below the national average. Every other Northeastern state scored above the national average on that index.
Hawaii was the most expensive state on the C2ER index for the second quarter of 2026, at 185.8, driven by a housing component more than three times the national average. On the BEA’s 2024 price parities, which cover all consumers statewide, California had the highest price level at 110.7, just ahead of Hawaii at 110.0.
It depends on the measure. On the BEA’s 2024 price parities, Mississippi had the second-lowest price level in the country, behind Arkansas. On the C2ER index, Mississippi ranked third in the first quarter of 2026 and sixth in the second. Shifts like that between quarters often reflect which cities were surveyed rather than real changes in prices.
Generally, yes. The BEA finds that state price levels and incomes tend to rise together. In most of the cheapest states, median household income remains below the national median even after adjusting for lower prices, with Iowa a notable exception. Low-cost states deliver the most benefit to people whose income does not depend on local wages, such as remote workers and retirees.
Among the 15 cheapest states on the C2ER index for the second quarter of 2026, Tennessee and Texas do not tax wage income. South Dakota, which ranked 21st on that index, also has no personal income tax. States without an income tax rely more on other taxes, such as sales or property taxes, so check the full tax picture for your situation.
It depends on your income, spending, and what you pay in taxes and insurance before and after the move. A difference in index points translates into a percentage difference in prices for the spending the index covers, not a percentage of your income. Subtract any loss of income and add back changes in taxes and insurance, then compare the result with the one-time cost of moving to see how long the move takes to pay for itself.
A score of 100 represents the national average. A score below 100 means prices are lower than average for the household the index measures, and a score above 100 means they are higher. A score of 85 means prices about 15 percent below average. C2ER cautions that small differences between scores should not be treated as meaningful.
Usually. The BEA’s 2024 data put prices in Missouri’s nonmetro counties at 83.9, nearly nine points below its metro counties at 92.6. Rural areas often trade lower housing costs for longer drives and fewer nearby services, including health care, so weigh those costs as well.
The Bottom Line
The most affordable states to live in are clustered in the South and the Midwest. On the latest state-level C2ER data, Oklahoma, Alabama, Iowa, West Virginia, and Kansas lead the list, and on the federal government’s own measure, Arkansas, Mississippi, Iowa, and Oklahoma have the lowest price levels. Any of the 15 states profiled here will stretch a fixed income further than the national average.
Choosing among them comes down to your situation. Iowa and Missouri pair low prices with incomes close to the national median. Mississippi, West Virginia, and Arkansas stretch a fixed income furthest. Tennessee and Texas favor working households with no state tax on wages. Oklahoma has the cheapest housing in the country but some of the highest homeowners insurance. Whichever states you are weighing, check taxes, insurance, utility bills, and income for the specific city you are considering, and run the break-even math with your own figures before you commit.
If your plan includes somewhere for your belongings to wait while you sell, close, or settle in, we make that part simple: rent online, get your access codes by email and text, and move in on your own schedule, month-to-month.
About the Author
10 Federal Storage
Our team at 10 Federal Storage has been in the self storage industry for decades. With knowledge gained from multiple universities and in the field, we are well-prepared and excited to assist with your storage needs. When you rent a unit with us, you can feel confident that our seasoned customer service team’s help will make your transition as seamless as possible. Customer satisfaction is our number one priority, and we strive to make your experience exceptional with our automated leasing options, diverse unit sizes, and a strong commitment to sustainability.